


The first went in in April 2011. They have been recording every half hour ever since — and for fourteen years the market that decides what your electricity costs read only the total. Forty-eight numbers a day, collapsed to one, and the shape put back on from one of eight national curves. That stopped last November, and the first thing the real data showed was a peak that wasn't there.
One thing to be clear about from the start: this is a story about houses. Britain's larger business sites have been settled on their actual half-hourly consumption for decades, and mid-sized ones since 2017. Offices, factories and shops have had a market that knows what they really did for as long as most of their meters have existed. It was homes — and only homes — that got the average.
Act 1 — the divergence is real, and nobody looks at it
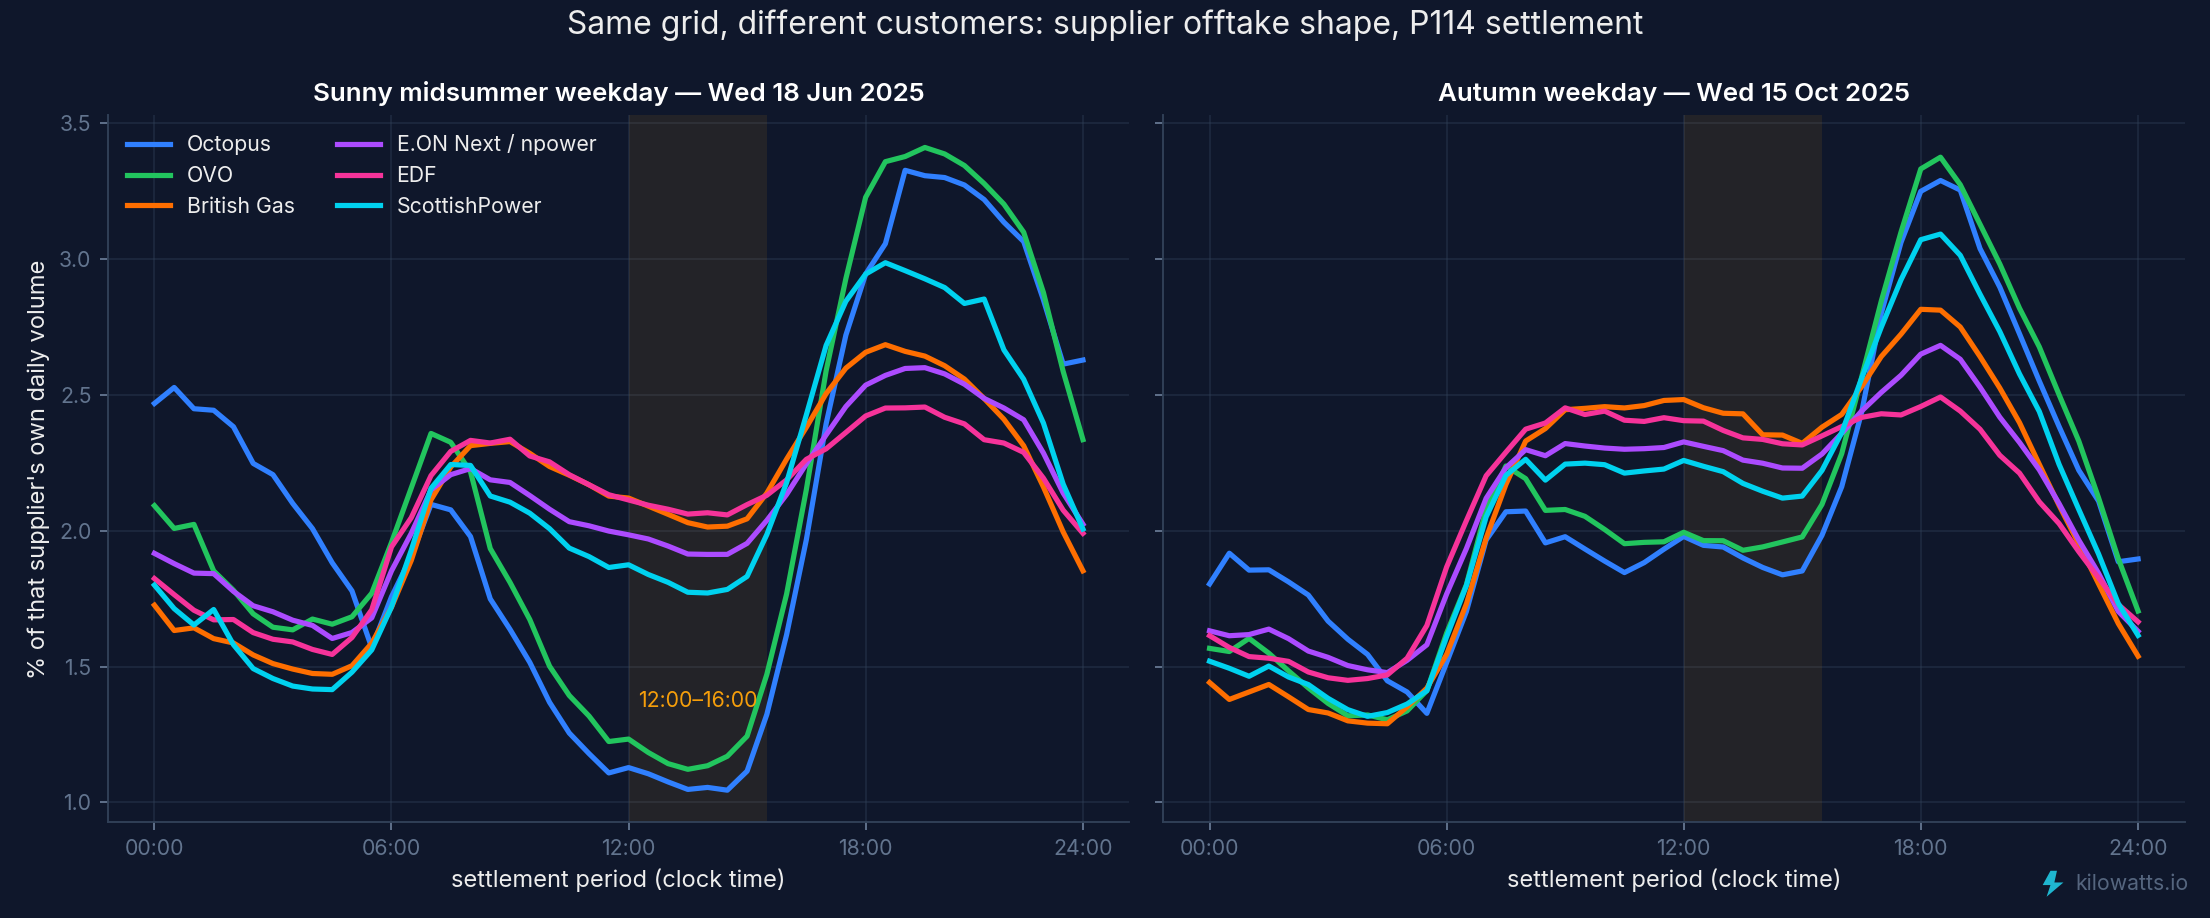
Wednesday 18 June 2025 and Wednesday 15 October 2025. Each line is normalised to the supplier's own day, so this is shape, not size — six companies selling identical electrons off the same wires to visibly different customers.
Elexon's P114 settlement files carry supplier × GSP region × half-hour metered volume for every supplier in GB, going back decades, free with a portal key. Almost nobody reads them.
On a sunny June weekday Octopus and OVO's midday volume collapses to about 1.05% of their own day per half hour. British Gas and EDF sit near 2.1%. By October all six lines lie on top of each other.
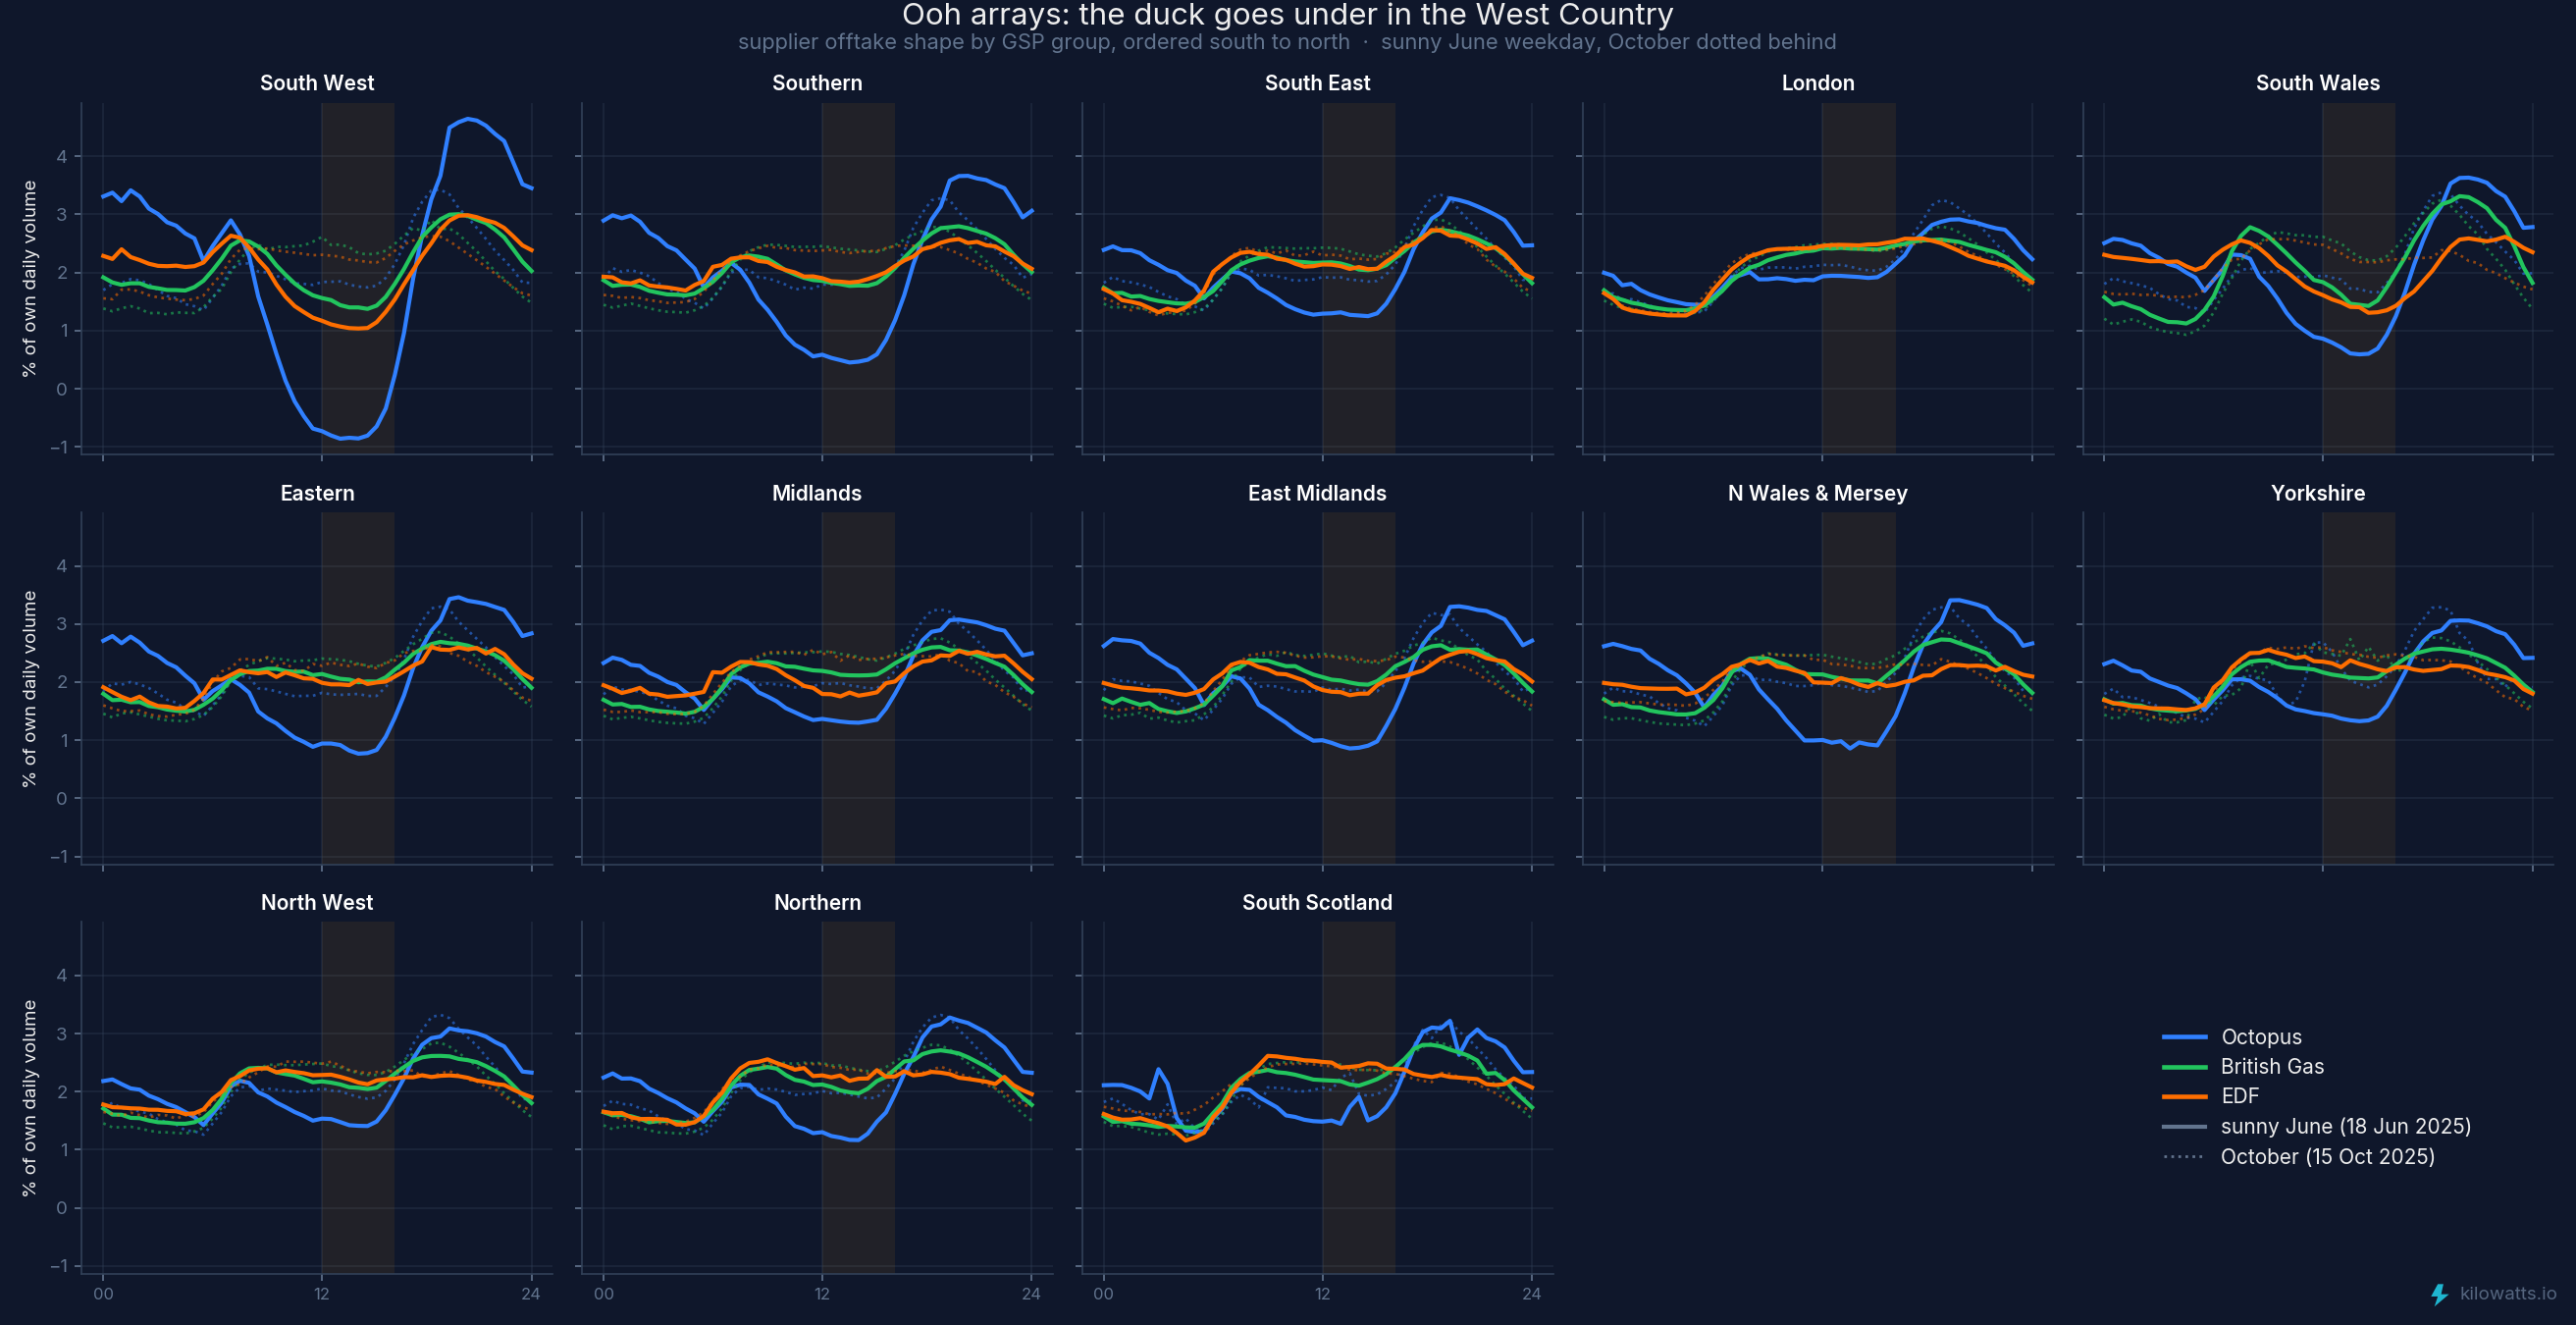
Ooh arrays. The same June Wednesday split fourteen ways, October dotted behind. The dip tracks irradiance and roof stock as you move north: about 1.5% of daily volume per half hour in South Scotland, 0.5% in Southern, below zero in the South West — and nothing at all in London.
In the South West, Octopus goes net negative at midday: its customers there export more than they import. In London there is no dip at all, for anyone. Flats have no roofs. That contrast is what proves this is solar and not tariff behaviour — a behavioural effect would show up in London too.
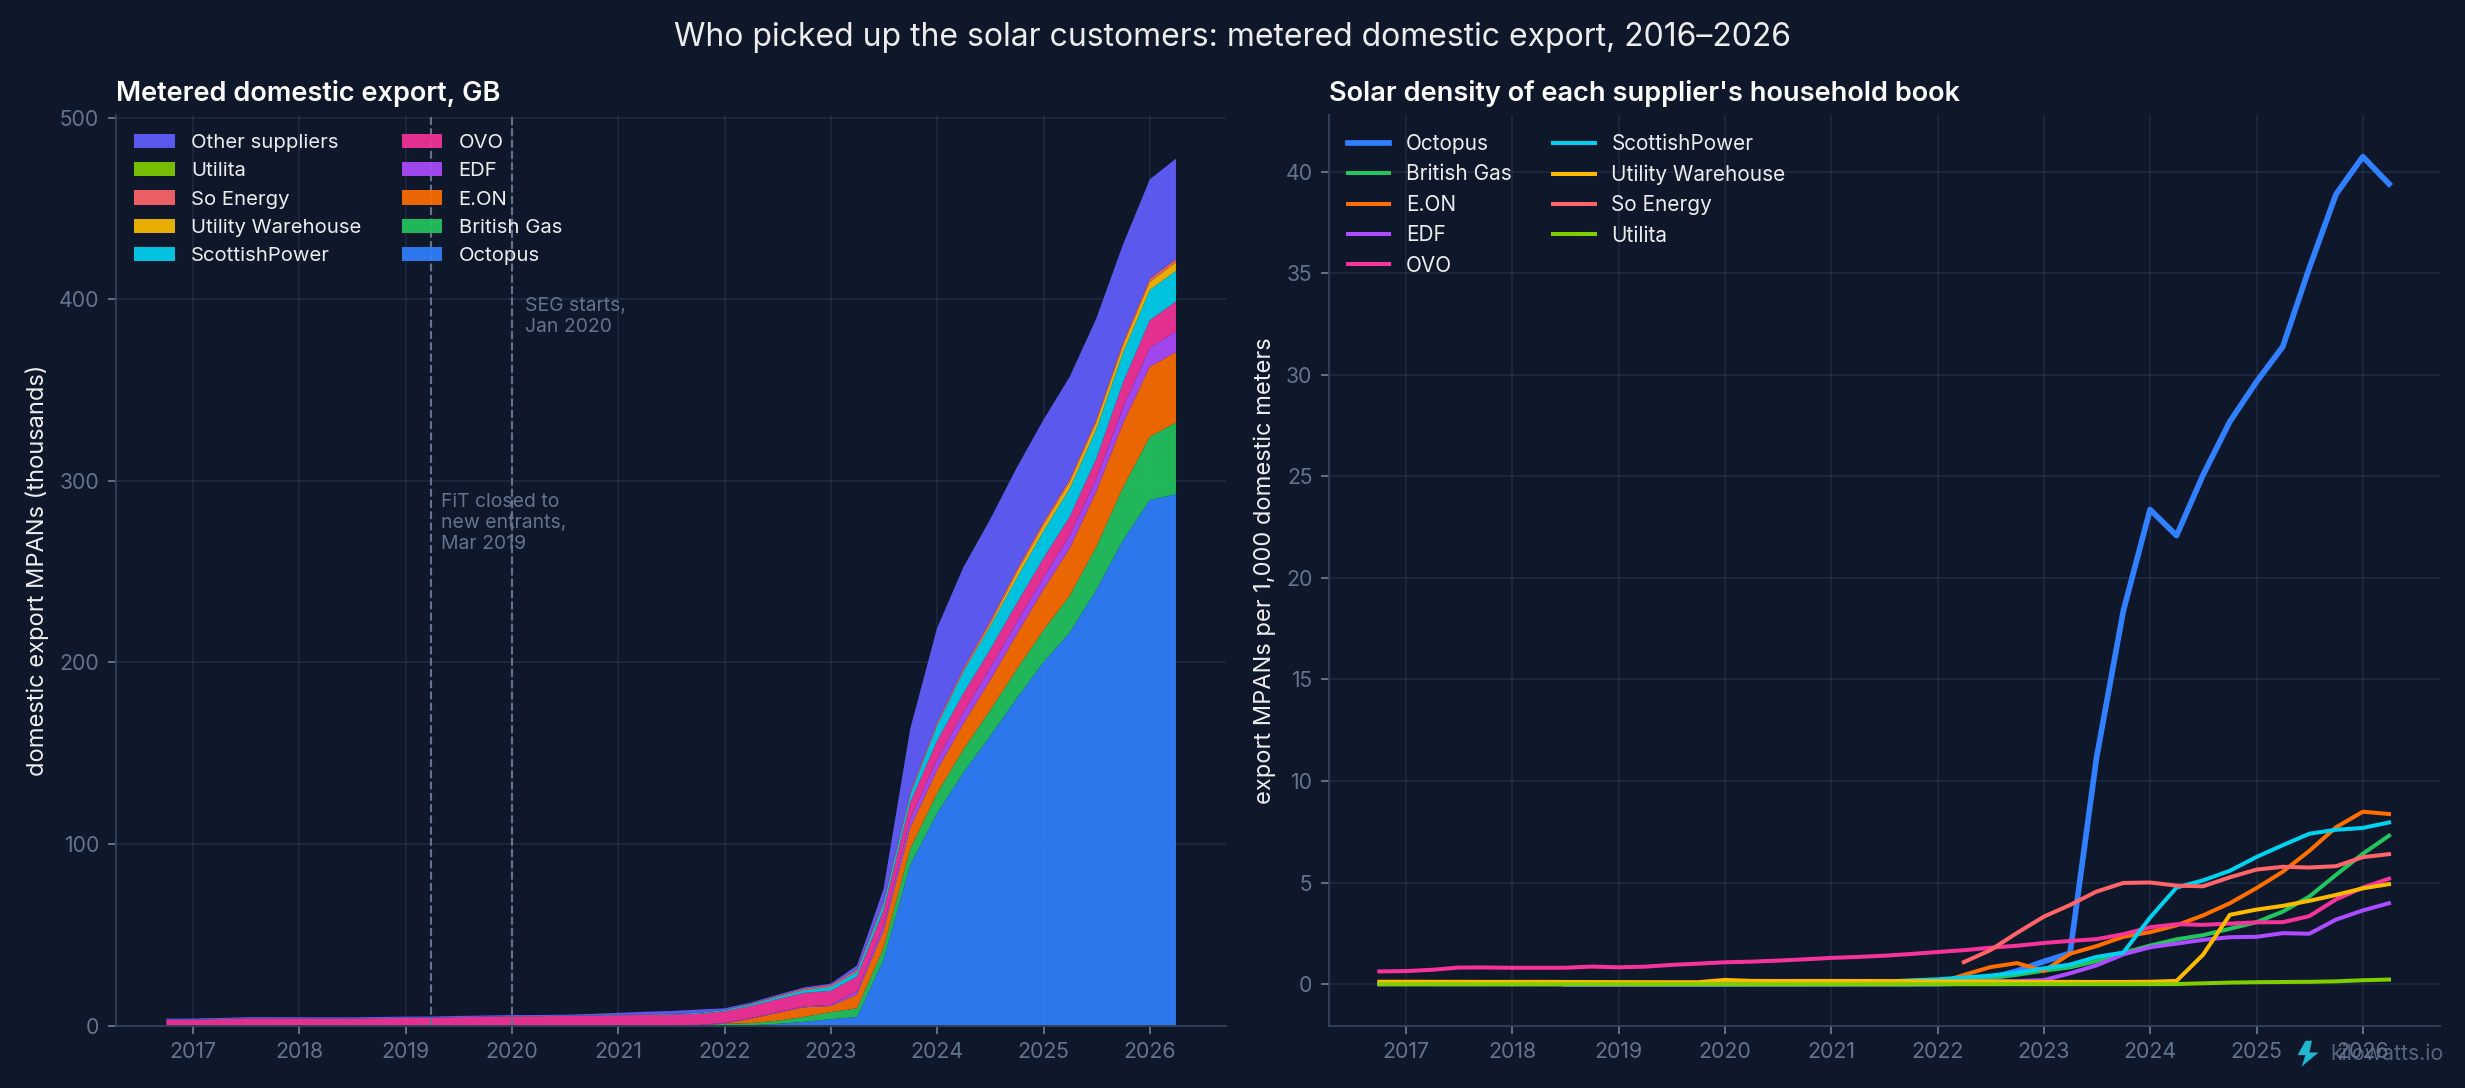
Metered domestic export sat at four to six thousand MPANs for five years, then went near-vertical from mid-2023. Octopus is roughly 61% of the 2026 stock and almost all of the growth.
The meter counts confirm it from a completely different direction: 39.4 domestic export MPANs per 1,000 domestic meters at Octopus, against 4.0 at EDF — and Octopus holds about 61% of every metered domestic export MPAN in Britain. One caveat to carry: under the Feed-in Tariff export was deemed, not metered, so part of that curve is existing solar homes being moved onto metered export rather than new panels. Octopus built the tariff that made registering worth doing, and took the registrations.
One distinction to hold throughout, because it trips people up. When this piece calls a book domestic or business, it means by volume, not by customer count. EDF is 24% domestic by volume — but 80% of its meters are households. Its business customers are simply enormous: a few thousand industrial sites outweigh two and a half million homes. British Gas is 56% domestic by volume and 83% by meters; E.ON 50% and 92%. Only at the pure ends do the two measures agree — Octopus 87% and 94%, Utilita 96% and 99%. Load shape is a volume-weighted thing, so volume is the right denominator here; but "EDF is a business supplier" means its energy is, not its customers.
The books differ on more than solar. Peak time runs as a clean scale — SmartestEnergy 09:00, Drax 10:30, EDF 16:30, British Gas 17:00, Octopus 18:00 — and Drax's evening share is 20.77% against a flat book's 20.83%, which is to say dead flat. The regional footprints are still frozen at privatisation: ScottishPower indexes 294 in South Scotland and 214 in Manweb, OVO 541 in North Scotland (the Scottish Hydro book it bought from SSE in 2020), EDF 151 in London. Octopus runs 68 to 132 everywhere — the only genuinely national book in GB, because it never inherited a monopoly.
Act 2 — except most of that was a fiction
Under legacy settlement, non-half-hourly meters were read — but only for the total. A meter reading, smart or otherwise, became an annual quantity of electricity, and settlement then spread that quantity across the 17,520 half hours of the year using coefficients from one of eight Profile Classes — national curves produced centrally from a few thousand sample meters. The arithmetic ran the wrong way round: the sum was measured and the shape was supplied. Every supplier in a region got the same shape.
Which is what makes the smart meter rollout such an odd artefact. A smart meter records 48 values a day. Settlement used one of them — the running total — and then told itself what the other 47 must have been. For fourteen years the distinguishing feature of a smart meter was, for this purpose, discarded on arrival.
Two numbers do the work here.
Utilita and Utility Warehouse — prepayment against multi-service bundle, about as different as two customer bases get — have settled shapes differing by a mean of 0.09 percentage points across all 48 periods.
And Utilita has one seventeenth of EDF's solar customers but twice the settled-shape solar response, because the profile classes carry average solar. The shape was mostly measuring how domestic you were.
Worth admitting in the piece: my own first reading of Octopus's fat overnight was that it was Economy 7 profile-class share. It wasn't — the step is at 23:30 in all fourteen regions, and Economy 7 windows are set regionally. It is Intelligent Octopus Go. But that is the mistake most readers will make, and making it in public is how you show the trap.
Act 3 — the fiction is being removed, live
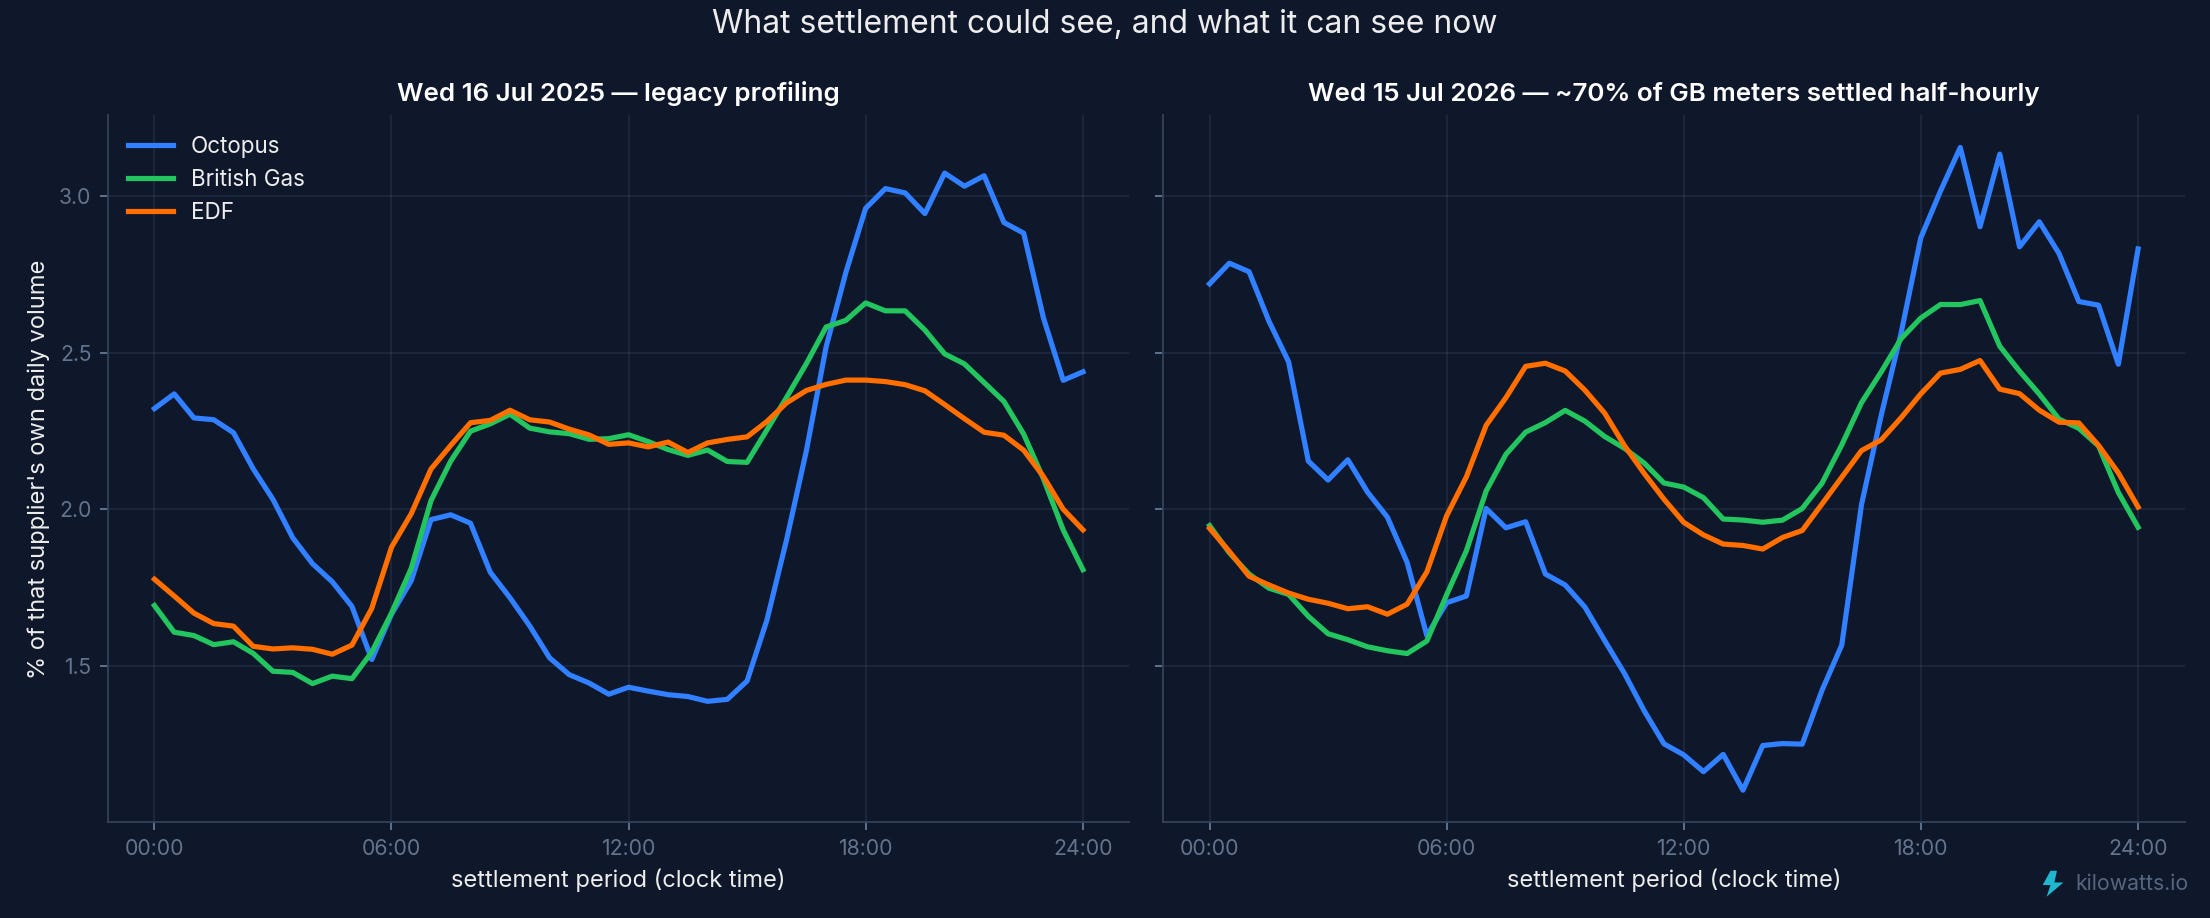
Two July Wednesdays, one year apart. In 2025 all three are smooth curves. In 2026, with about 70% of GB meters settled half-hourly, British Gas and EDF are still smooth and Octopus is not.
Market-wide Half Hourly Settlement migration: ≈0 meters in November 2025, 2m by February 2026, 7m by April, 20.6m by August — about 70% of GB.
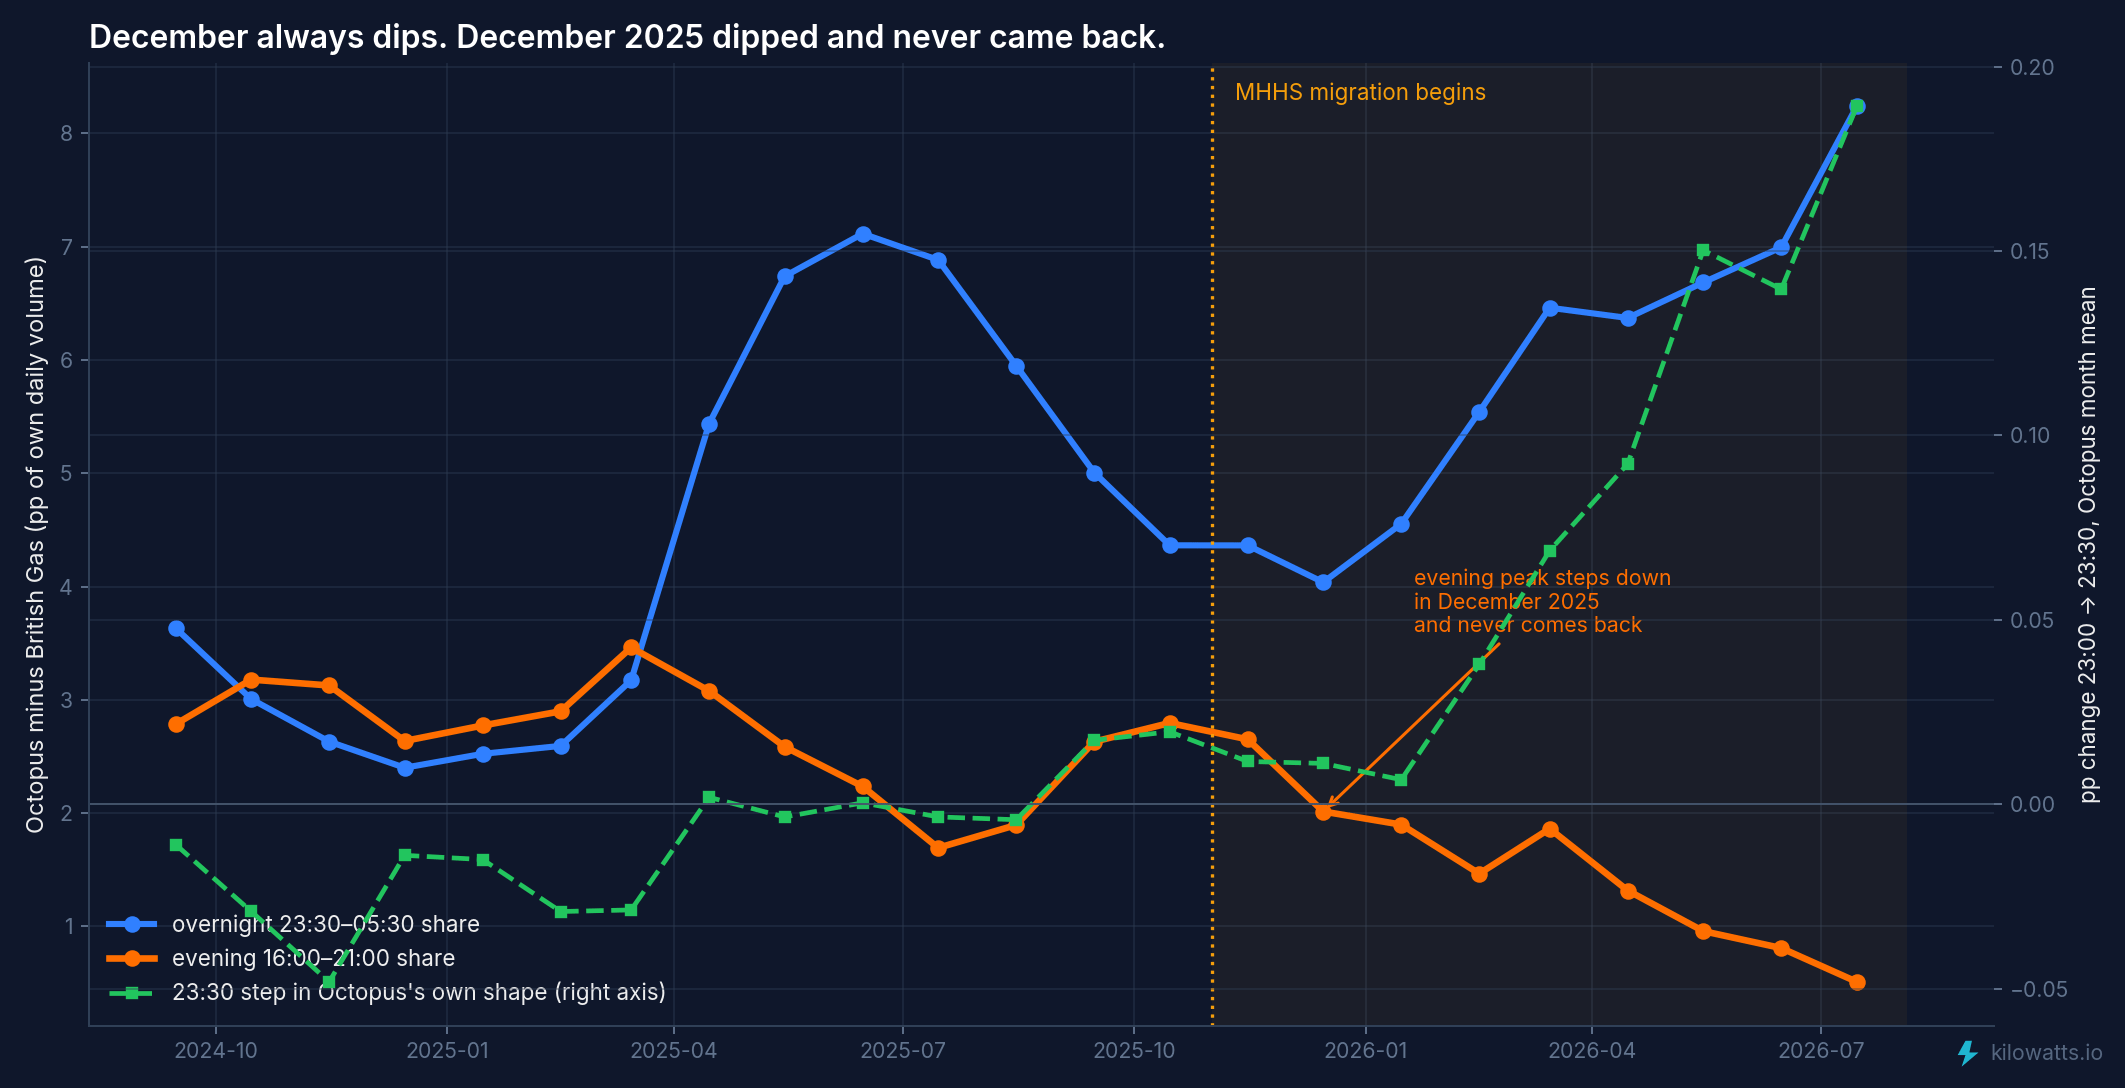
December always dips — look at December 2024, which recovers to the highest gap of the series by the following March. December 2025 dipped and never came back. The dashed line is the 23:30 fingerprint arriving.
The fingerprint is at 23:30. Octopus's month-mean volume neither rose nor fell at 23:30 through all of 2025. Then it climbs monotonically through 2026 — +0.01, +0.04, +0.07, +0.08, +0.14, +0.14, +0.19 — tracking the migration curve. Every other supplier's volume falls at 23:30, as you would expect late at night. Octopus's rises, because that is when its EV customers plug in and settlement can finally see it.
Octopus front-ran the reform. Elective half-hourly settlement of its own domestic smart meters went 5,900 meters in 2021 Q1 → 190,000 in 2023 Q1 → 624,000 by 2025 Q3. It was paying to be measured years before it had to be.
Act 4 — the peak that wasn't there
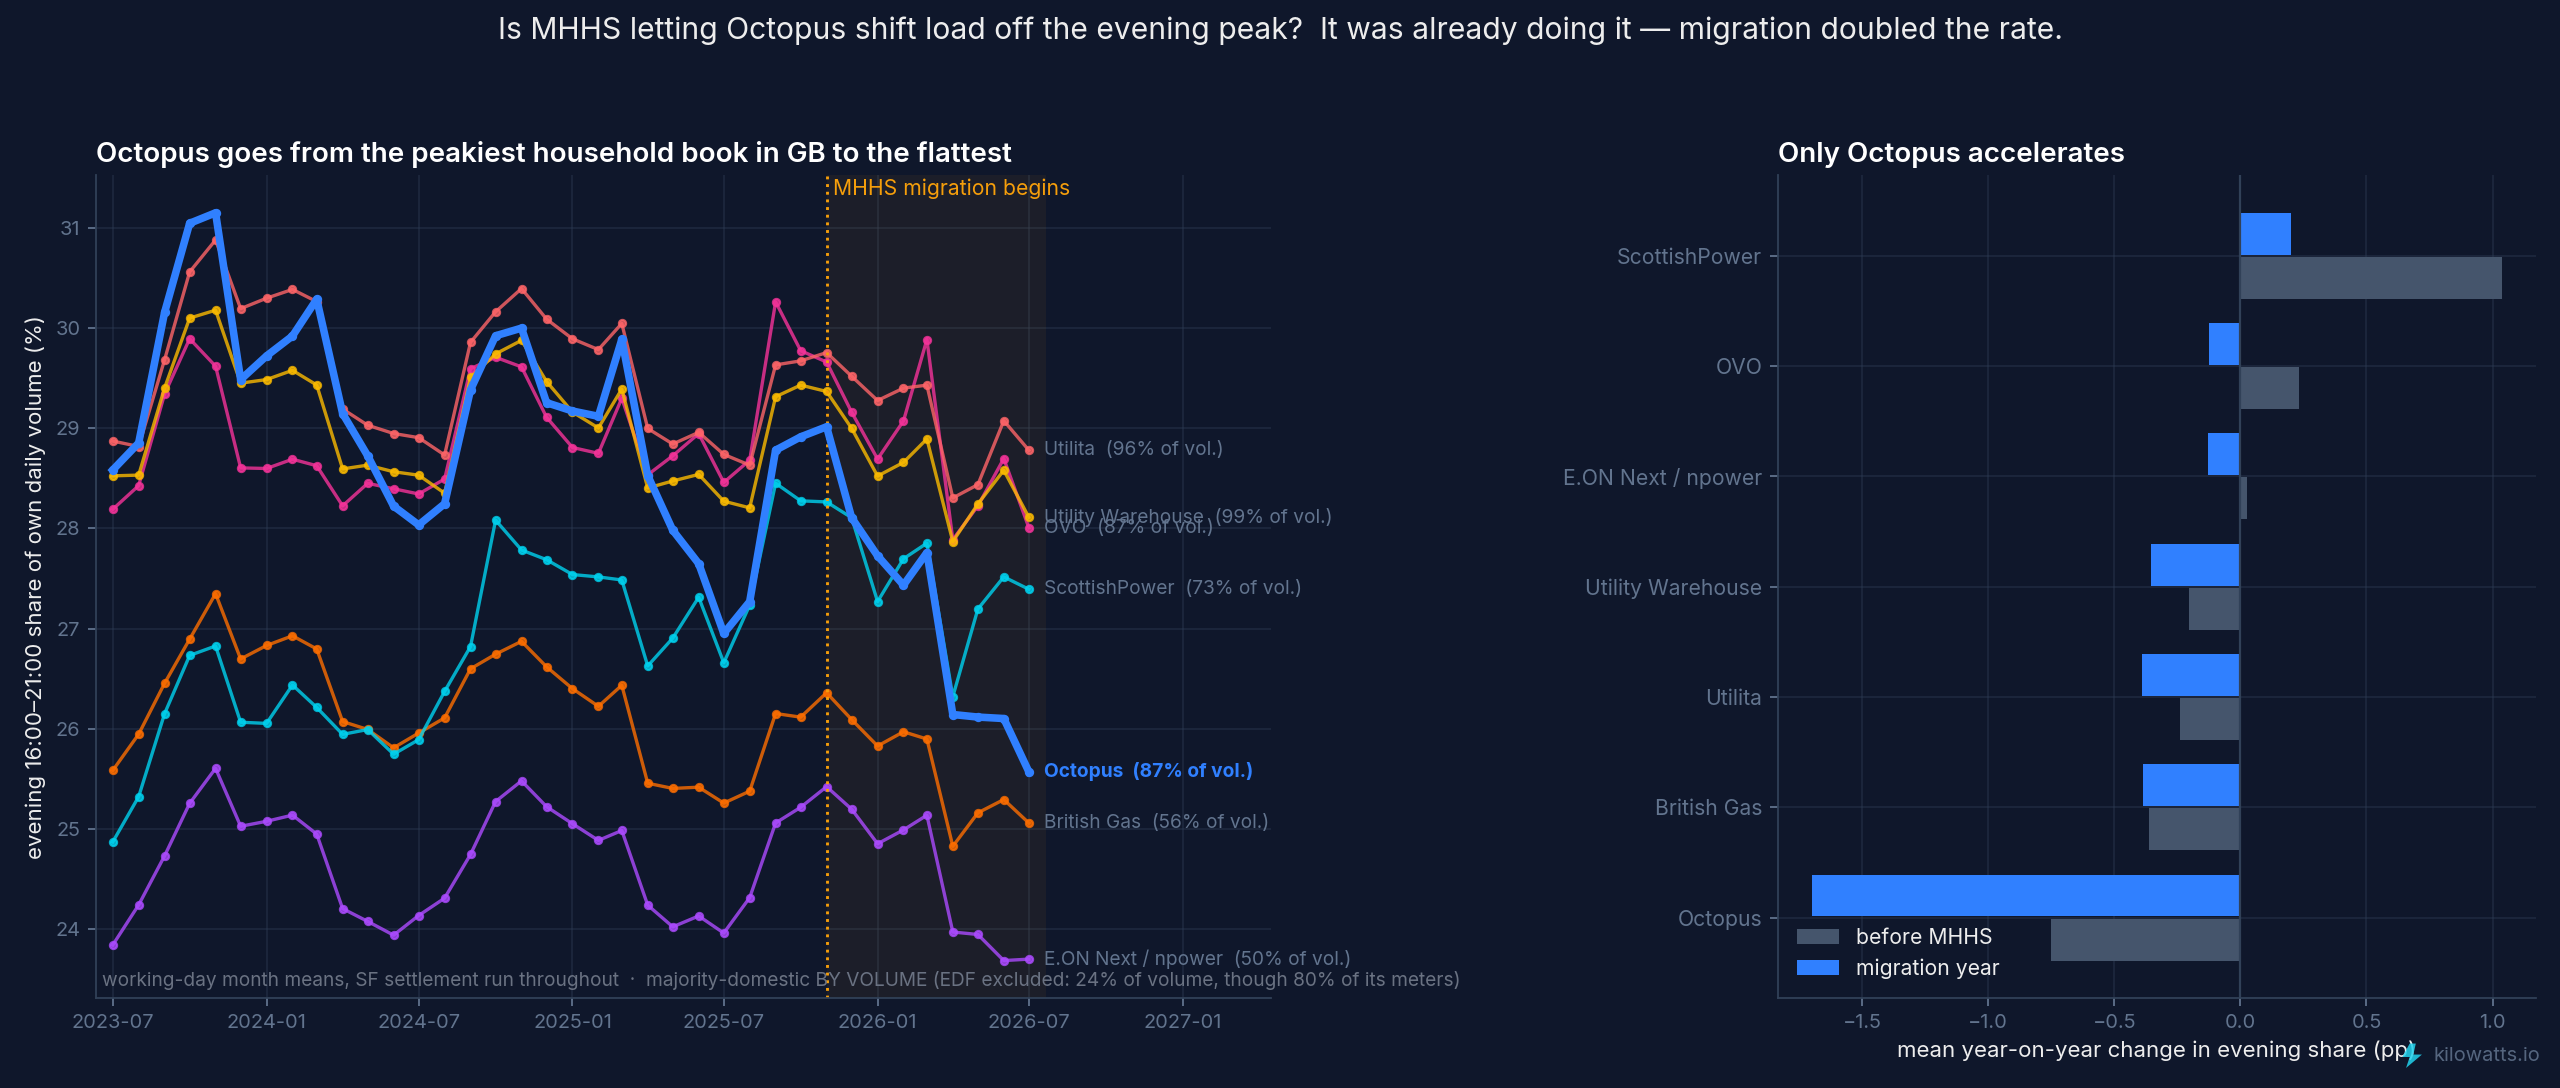
Thirty-seven consecutive months, working days, one settlement run throughout. Octopus crosses down through the entire household pack. Every other majority-domestic supplier moves less than 0.6 points in three years, and none of them accelerates at migration.
Octopus has gone from the peakiest household book in GB to the flattest. Its evening 16:00–21:00 share fell from 28.58% in July 2023 to 25.57% in July 2026. On matched twelve-month windows the move is 2.20 points. Every other majority-domestic supplier moved less than 0.6 points.
The rate is the tell: −0.75 points a year before MHHS, −1.70 a year during migration — 3.5 standard deviations from Octopus's own pre-reform baseline. Nothing else in the residential group passes 2.
Octopus's customers were already flatter than the standard profile. Profiling could not see that, so it settled Octopus against a national evening peak its customers did not have. Octopus's customers were cross-subsidising peakier books. Migration is what stops it.
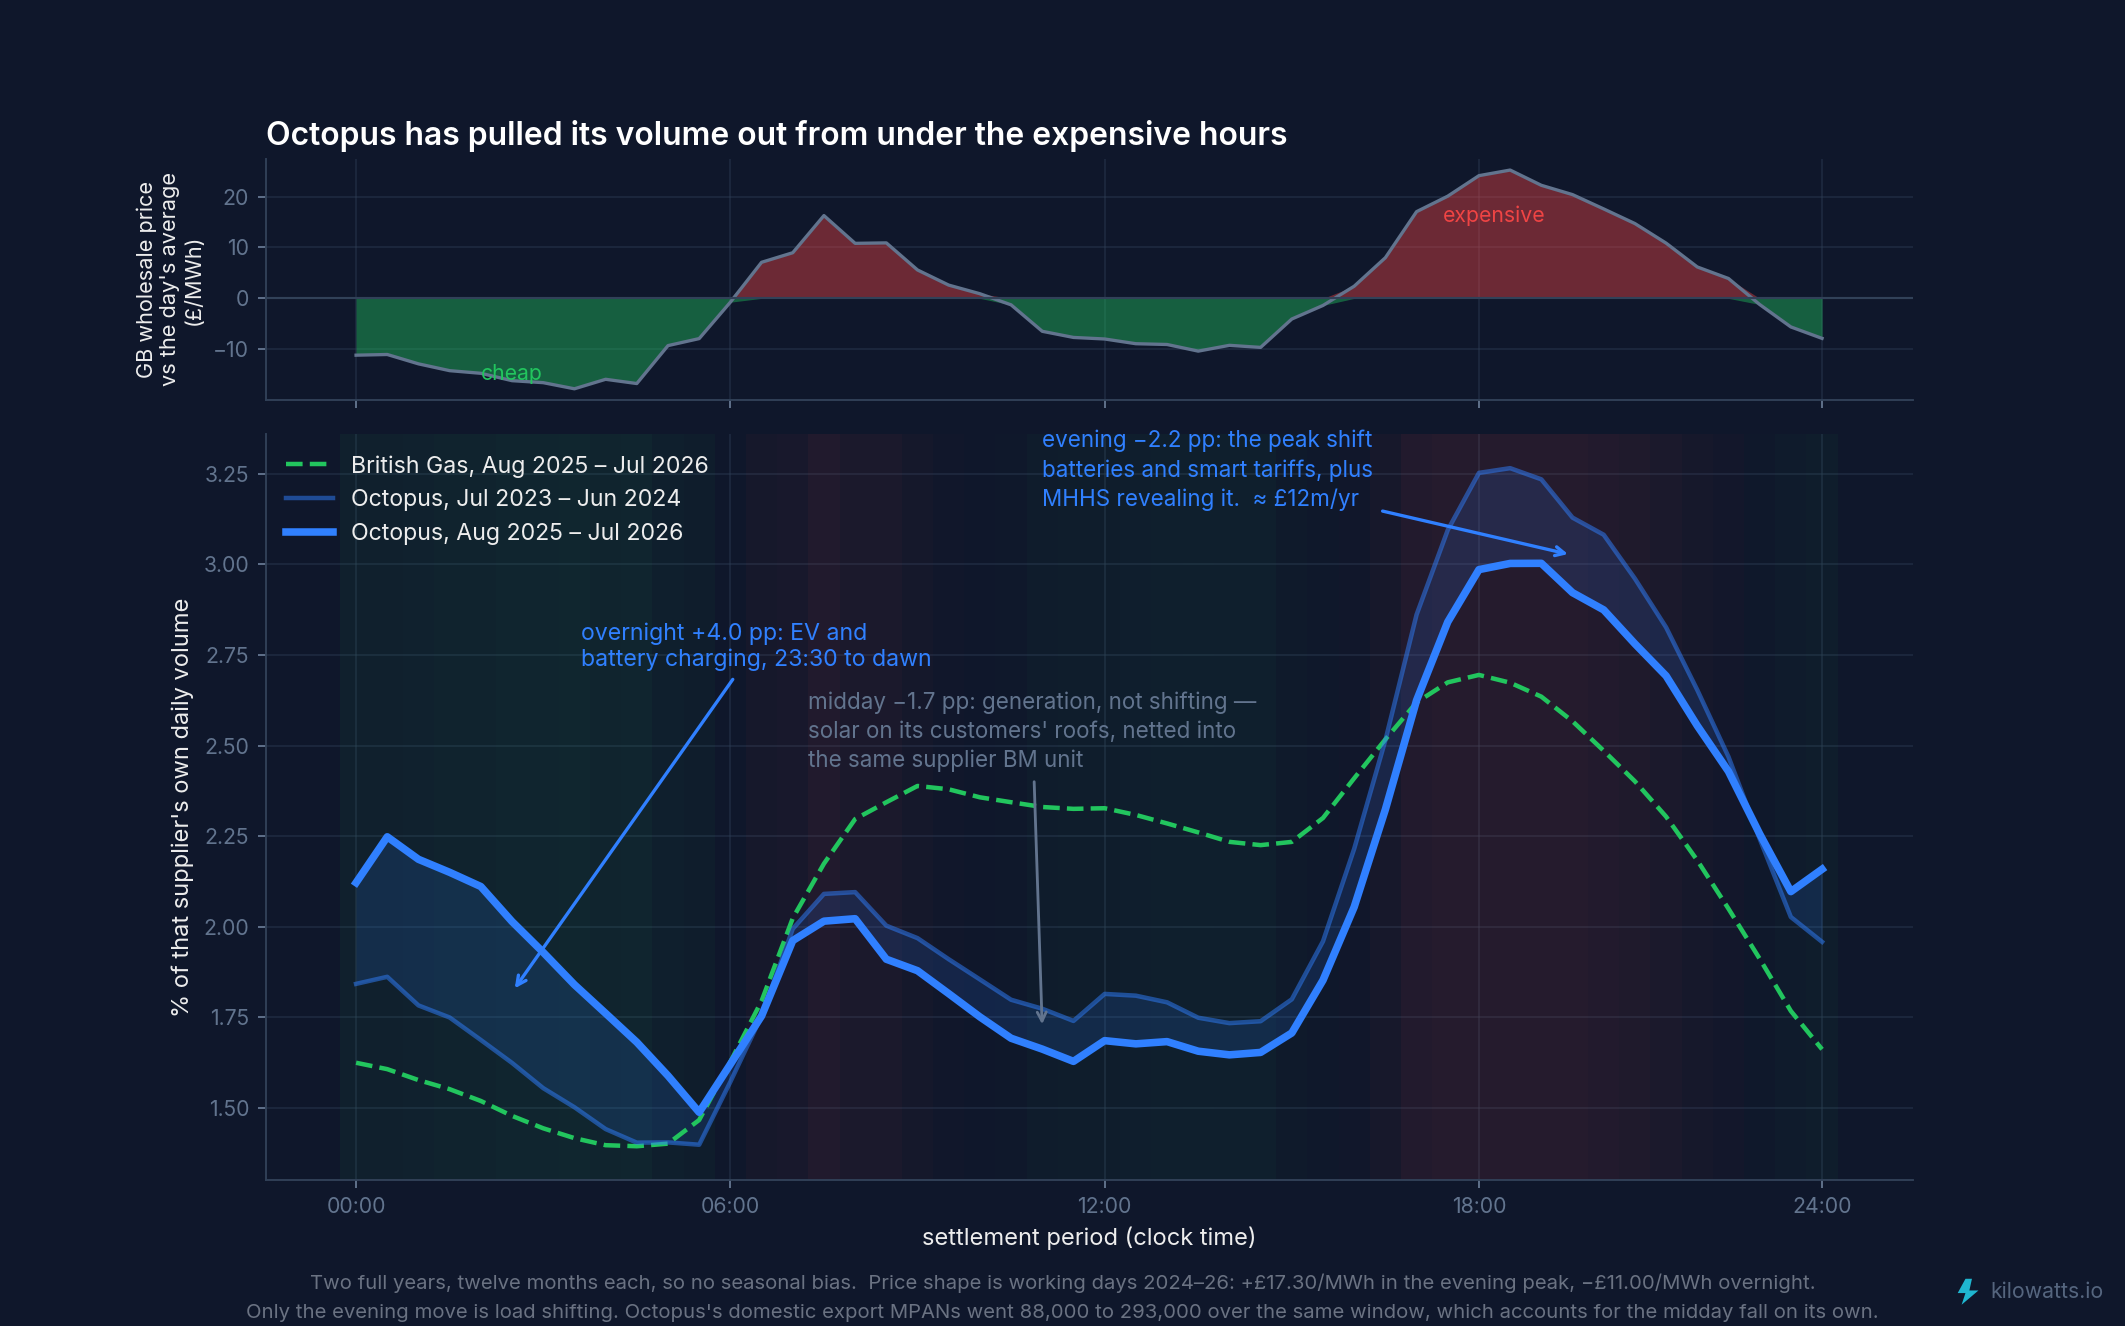
The price curve, in its own panel, is why shape costs money: +£17.30/MWh in the evening peak, −£11.00/MWh overnight, working days 2024–26.
And here is what it is worth. Britain's wholesale evening peak runs £17.30/MWh above the day's average and the overnight trough £11.00/MWh below it — a spread of £28.29. Octopus's implied 2026 volume is 30.5 TWh, so one percentage point of evening share is 305 GWh a year. The 2.20-point move is £11.6m a year at the evening premium, £19.0m against the full spread.
Three separate mechanisms are in that chart, and only one of them is load shifting:
06:00–16:00 — change: −1.7 pp · what it is: generation, not shifting — solar netted into the same BM unit
16:00–21:00 — change: −2.2 pp · what it is: the peak shift — batteries and smart tariffs, plus MHHS revealing it
23:30–06:00 — change: +4.0 pp · what it is: EV and battery charging
Only the evening move is worth the £11.6m. Octopus's export MPANs went from 88,000 to 293,000 over the same window, which accounts for the midday fall on its own. Getting this wrong — crediting the whole 4-point move to load shifting — would roughly double the number.
Two of those three mechanisms are still running and one has finished. The solar gap is now enormous and static: Octopus took 16.5% of its summer day between 10:00 and 15:30 last year and 16.6% this year, against 21.3% and 21.2% for the rest of the household pack. Panels made Octopus's summer look different, and they did that some years ago. The overnight move has not stopped — and it shows up most starkly in the season where Octopus still looked ordinary. Between 23:00 and 05:30 last winter Octopus took 17.2% of its day; this winter, 19.6%. The other eight went from 16.3% to 16.0%. A book that was within a point of everyone else overnight in the dead of winter is now two and a half points clear of it, and that is the half of the day where there is no sun to explain it.
Honest limit: this values the shape at wholesale prices. It is what the volume costs to buy, not a transfer anyone writes a cheque for. And splitting the move into "behaviour" and "measurement" assumes the pre-MHHS trend would have continued, which is an assumption rather than an observation.
Act 5 — everyone else did something different
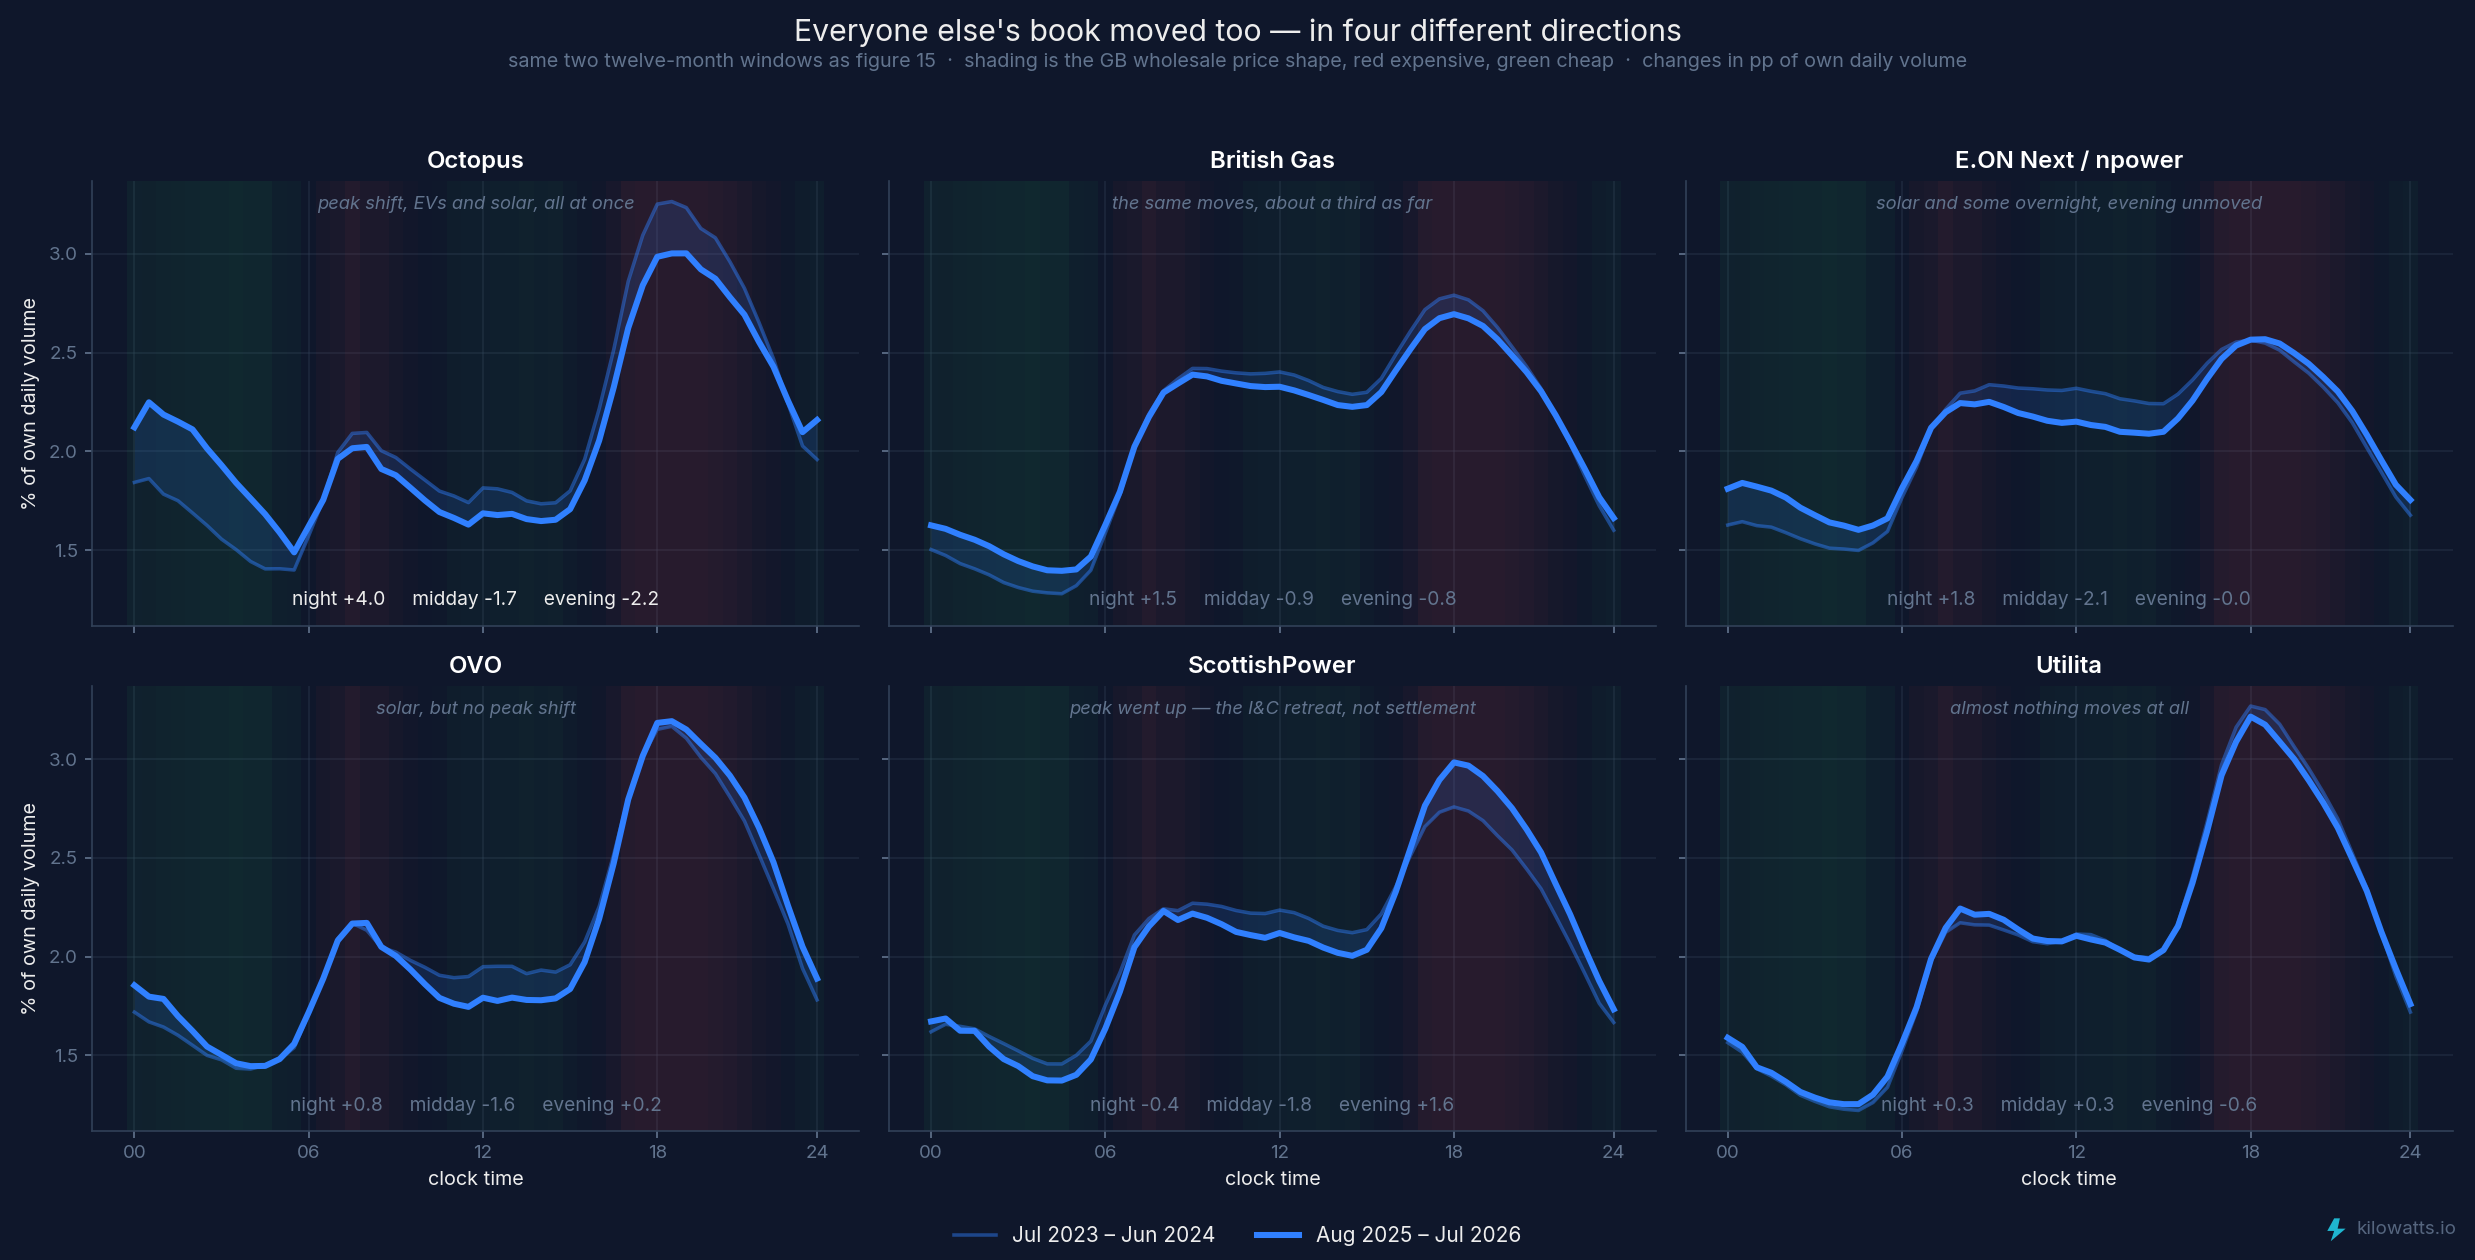
Same two twelve-month windows, same price shading. The other suppliers are not smaller Octopuses.
Octopus — night: +4.0 · midday: −1.7 · evening: −2.2 · peak shift, EVs and solar at once
British Gas — night: +1.5 · midday: −0.9 · evening: −0.8 · the same three moves, a third as far
E.ON — night: +1.8 · midday: −2.1 · evening: −0.0 · solar and some overnight, evening unmoved
OVO — night: +0.8 · midday: −1.6 · evening: +0.2 · solar, but no peak shift at all
ScottishPower — night: −0.4 · midday: −1.8 · evening: +1.6 · peak went up
Utilita — night: +0.3 · midday: +0.3 · evening: −0.6 · almost nothing moves
Every book except Utilita's loses midday volume. That is GB-wide embedded solar, not any supplier's strategy — E.ON's −2.1 points is the largest of the six.
ScottishPower is the control. It is the only large household book whose peak went up, and it is not a settlement effect at all: its non-domestic volume fell from 2.45 TWh in 2022 Q1 to 0.77 TWh in 2026 Q1, down 69%, taking its domestic share of volume from 55% to 73%. Strip out the flat 24/7 industrial load that used to dilute the peak and the household peak stands out more. Nothing about its customers changed; the denominator did. That is what a shape change looks like when the cause is ordinary commercial retreat — gradual, starting years earlier, no acceleration at migration. It is the contrast that makes the Octopus result convincing rather than merely striking.
Act 6 — is Octopus actually greener?
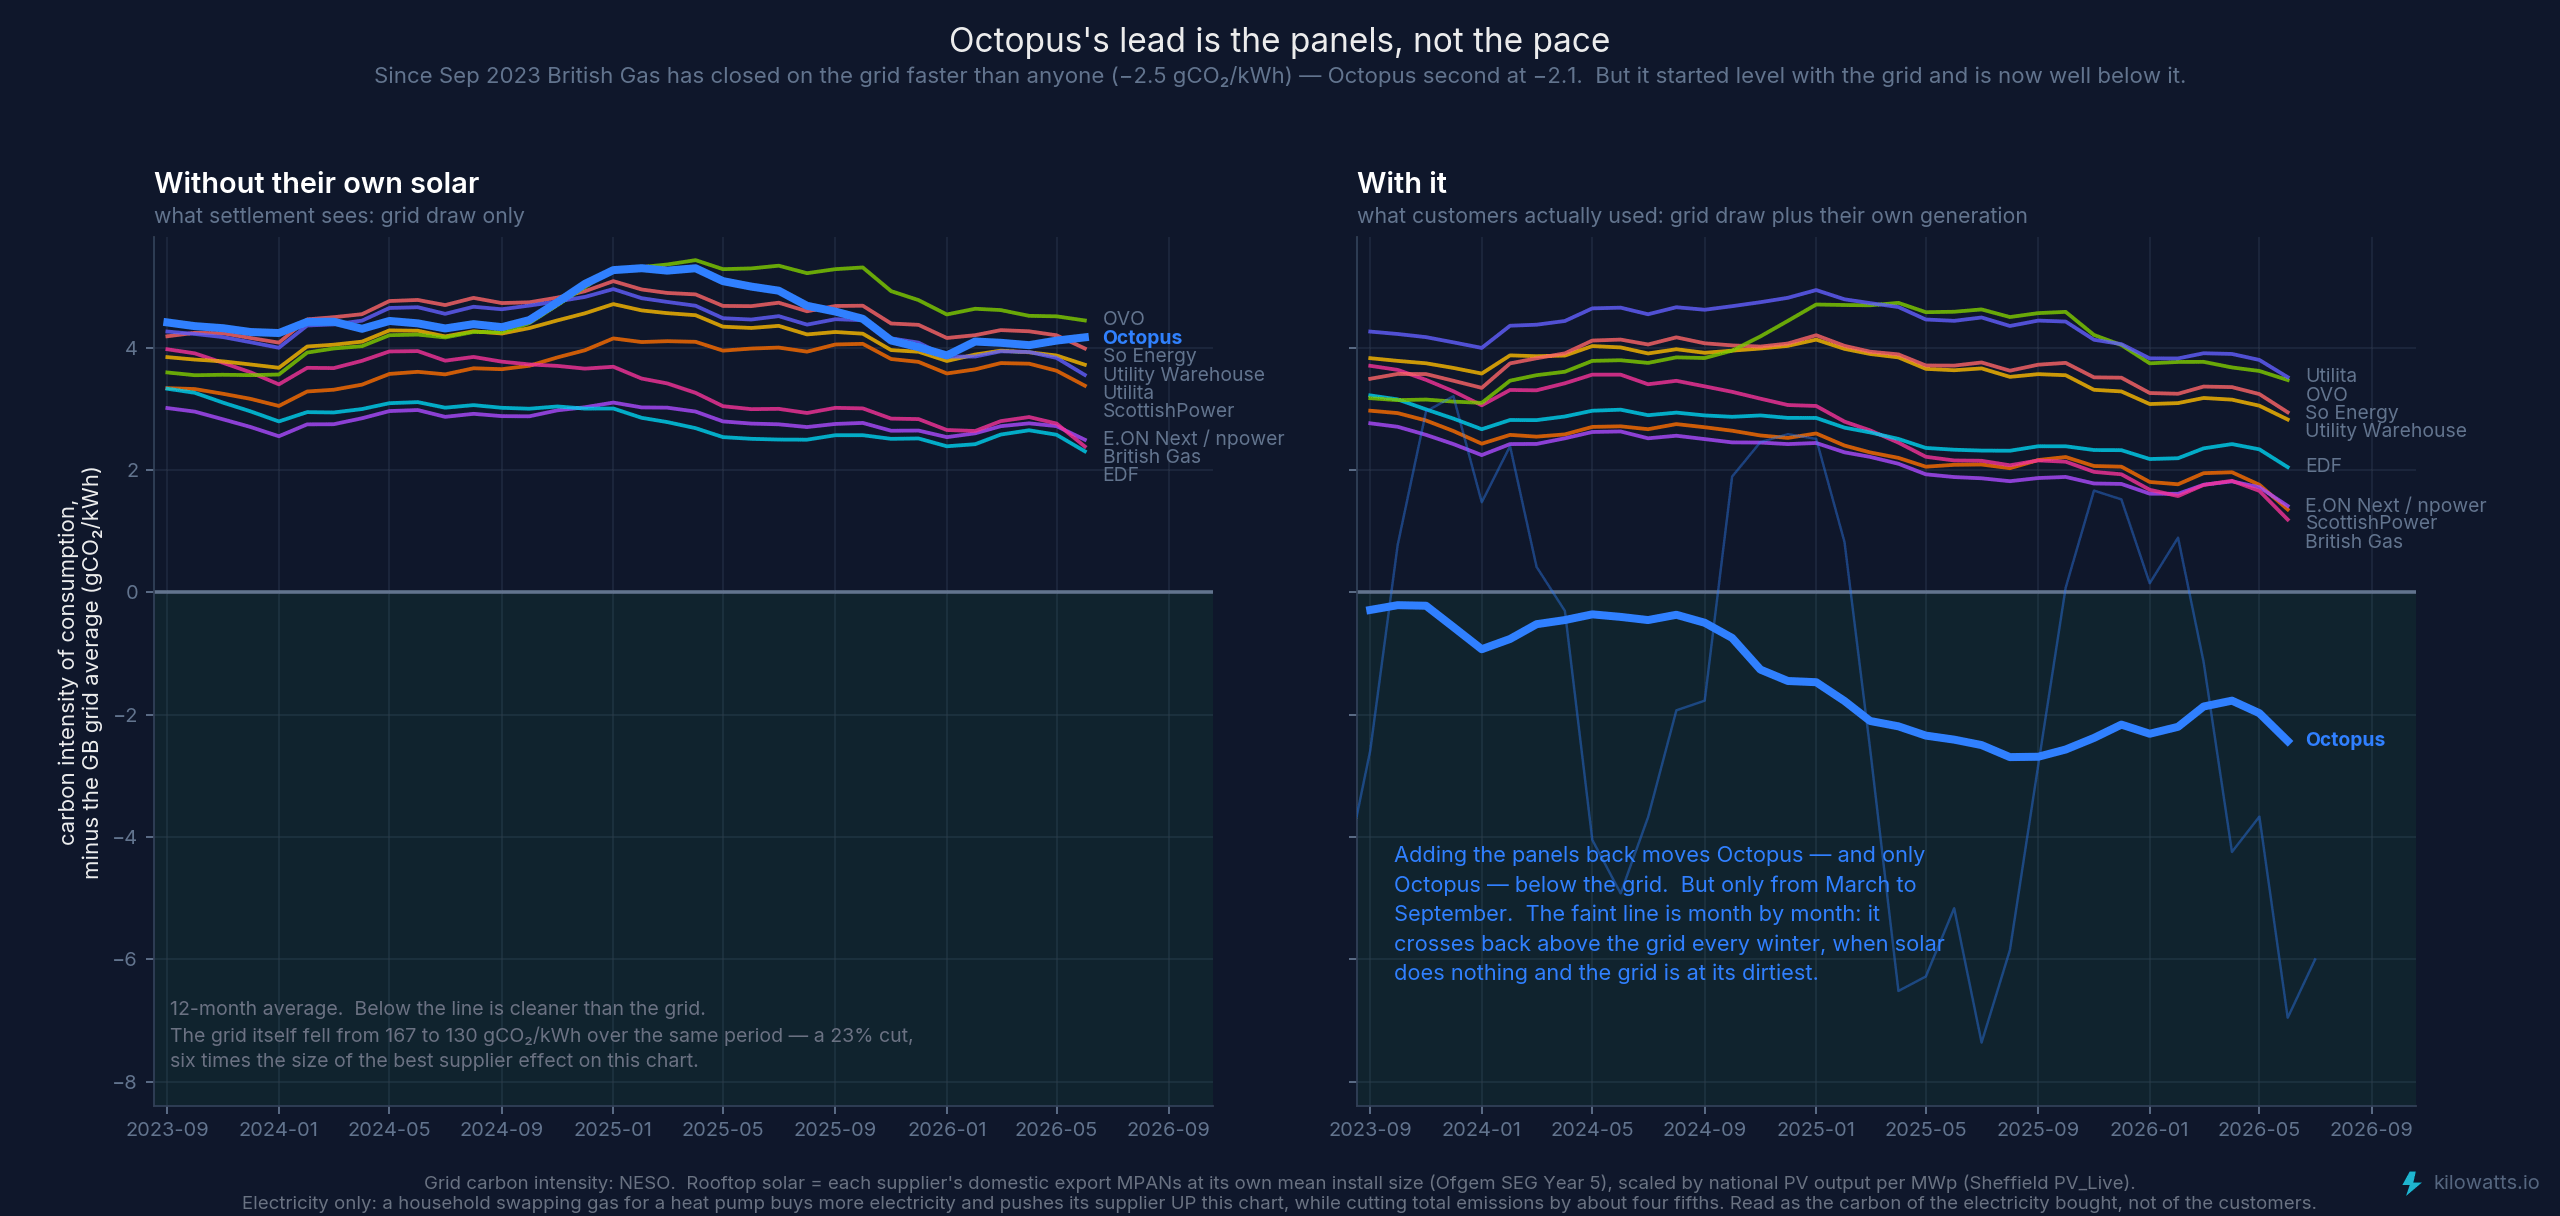
2026 averages. Grid carbon intensity from NESO; rooftop solar from each supplier's domestic export MPANs at that supplier's own mean install size, taken from Ofgem's SEG installation dataset, scaled by national PV output.
So far this has all been about when people use electricity. The obvious next question is whether any of it is cleaner — and the obvious answer is wrong twice over.
On grid draw alone — which is all settlement sees — Octopus looks the worst of the lot. Its customers pull 134.2 gCO₂/kWh against British Gas's 132.8 and EDF's 132.5. Every domestic supplier is above the grid average of 130, because households are peakier than the system and peaks are gas. But Octopus is worse than most, for a perverse reason: its customers self-supply through the middle of the day, so they skip the grid's cleanest hours. Per unit taken from the grid, what is left is dirtier.
A second effect pulls the same way, and it is the subject of Act 7: Octopus's book has more electrified heat than any other major. Heating runs on winter evenings — the dirtiest hours of the dirtiest months. So the two things this supplier is doing that you would most want a supplier to do, putting panels on roofs and heat pumps in houses, both push it up the only carbon measure settlement can see.
Add their own generation back — settled volume is consumption minus generation, so consumption is settled plus generation — and the ranking inverts. Octopus goes to 127.9 gCO₂/kWh, the cleanest book in Britain, and the only one whose customers' electricity is, on an annual average, cleaner than the grid they draw it from.
On an annual average is doing a lot of work in that sentence. Solar is seasonal, and violently so: Octopus's rooftop fleet removes 11.1 gCO₂/kWh in July and 1.1 in December, a tenfold swing. Take it month by month rather than as a rolling year and Octopus sits below the grid from March to September and back above it from October to February. The advantage disappears in precisely the months it would matter most — when the grid is dirtiest, demand is highest, and, for a book with more electric heating than anyone's, its customers are using the most.
But it is a lead built on stock, not speed. Measured on how much each book has closed on the grid since September 2023, British Gas has improved faster than Octopus — −2.5 gCO₂/kWh against −2.1, and on grid draw alone Octopus is fifth of nine and barely moves at all. Its own solar makes its customers skip the grid's cleanest hours, which cancels most of what it gains by shifting load off the evening peak. Octopus is far ahead because it acquired the panels, not because it is pulling away.
The gap between the two measures is the cleanest single statistic in the piece: gCO2/kWh removed by a supplier's own rooftop solar, twelve months to July 2026.
Octopus — gCO₂/kWh removed: 6.30 · behind Octopus: —
ScottishPower — gCO₂/kWh removed: 1.88 · behind Octopus: 3.4×
British Gas — gCO₂/kWh removed: 1.06 · behind Octopus: 5.9×
E.ON — gCO₂/kWh removed: 0.99 · behind Octopus: 6.4×
So Energy — gCO₂/kWh removed: 0.96 · behind Octopus: 6.6×
OVO — gCO₂/kWh removed: 0.87 · behind Octopus: 7.2×
Utility Warehouse — gCO₂/kWh removed: 0.79 · behind Octopus: 7.9×
EDF — gCO₂/kWh removed: 0.23 · behind Octopus: 27×
Utilita — gCO₂/kWh removed: 0.03 · behind Octopus: 201×
So: ScottishPower is Octopus's closest competitor on greening its customers' electricity — at about a third. Nobody is close.
And now the deflation, because it matters more than any of the above. Six grammes per kilowatt-hour sounds like a lot until you put it against the number underneath it. Octopus's entire rooftop fleet — 314,000 installations, the largest in Britain by a factor of twelve — removes 4.7% of its customers' electricity emissions. British Gas's removes 0.8%. Utilita's removes 0.02%.
Over the same three years the grid itself went from 167 to 130 gCO₂/kWh: a 23% cut. The grid did six times more for Octopus's customers than Octopus's entire solar fleet did.
That is the proportion to hold on to. Everything in this article — the solar, the batteries, the smart tariffs, the peak shifted off the evening — is happening in the margins of a number being driven overwhelmingly by what is connected to the transmission system. It matters for who pays what, and it is a real and growing commercial divide between suppliers. It is not, on this evidence, how Britain decarbonises its electricity. That was done by building wind farms.
Install sizes come from Ofgem's Smart Export Guarantee dataset, which records every SEG installation's capacity by licensee. It is worth reading on its own: Octopus holds 314,470 of Britain's 405,439 SEG solar installations — 78% of them — and its share sits between 74% and 80% in every single region. Its systems are also the smallest of the majors, averaging 5.36 kW against British Gas's 7.70 and ScottishPower's 7.78: mass-market suburban roofs rather than large rural arrays.
One caveat that runs the other way, and it is a big one. This measures the carbon of electricity, and electricity is only part of a household's energy. A home that swaps a gas boiler for a heat pump uses far more electricity — which makes its supplier look worse on this chart — while cutting its total emissions sharply. Gas heat costs about 215 gCO₂ per kWh delivered once boiler losses are counted; the same heat from a heat pump at a seasonal efficiency of three, on a 130 gCO₂/kWh grid, costs about 43. Roughly a fifth.
That matters here because the suppliers with the most electric heating are the same ones that top this chart's grid-draw column. Octopus's demand rises 6.1% per heating degree day and OVO's 6.2%, against British Gas's 4.2% and EDF's 3.5% — they are carrying more of Britain's heat on the wire rather than in a pipe. An electricity-only carbon metric penalises exactly the thing you want suppliers to be doing. Read this chart as "the carbon of the electricity they bought", never as "the carbon of their customers".
Three further things it deliberately does not do.
It ignores REGOs and green tariffs, which are a contractual matter and tell you nothing about when anyone consumed.
It undercounts solar, everywhere. Panels installed under the Feed-in Tariff have deemed export — a flat assumption, never metered — so those homes hold no export MPAN and appear in neither Elexon's counts nor Ofgem's SEG dataset. Their generation still suppresses their supplier's settled volume; this measure simply cannot see it. GB domestic rooftop is usually put at 4.5–5 GW, and the metered export fleet modelled here is about 1.9 GW. Every solar figure in this article is a floor, and most of all for whoever holds the legacy FiT book — which, given when those panels went up, means the incumbents rather than Octopus.
And it does not tell you whether Octopus made its customers greener or simply attracted the ones who already were. A large part of that export MPAN curve is FiT-era homes re-registering onto metered export, not new panels going up.
Act 7 — where the gas grid runs out
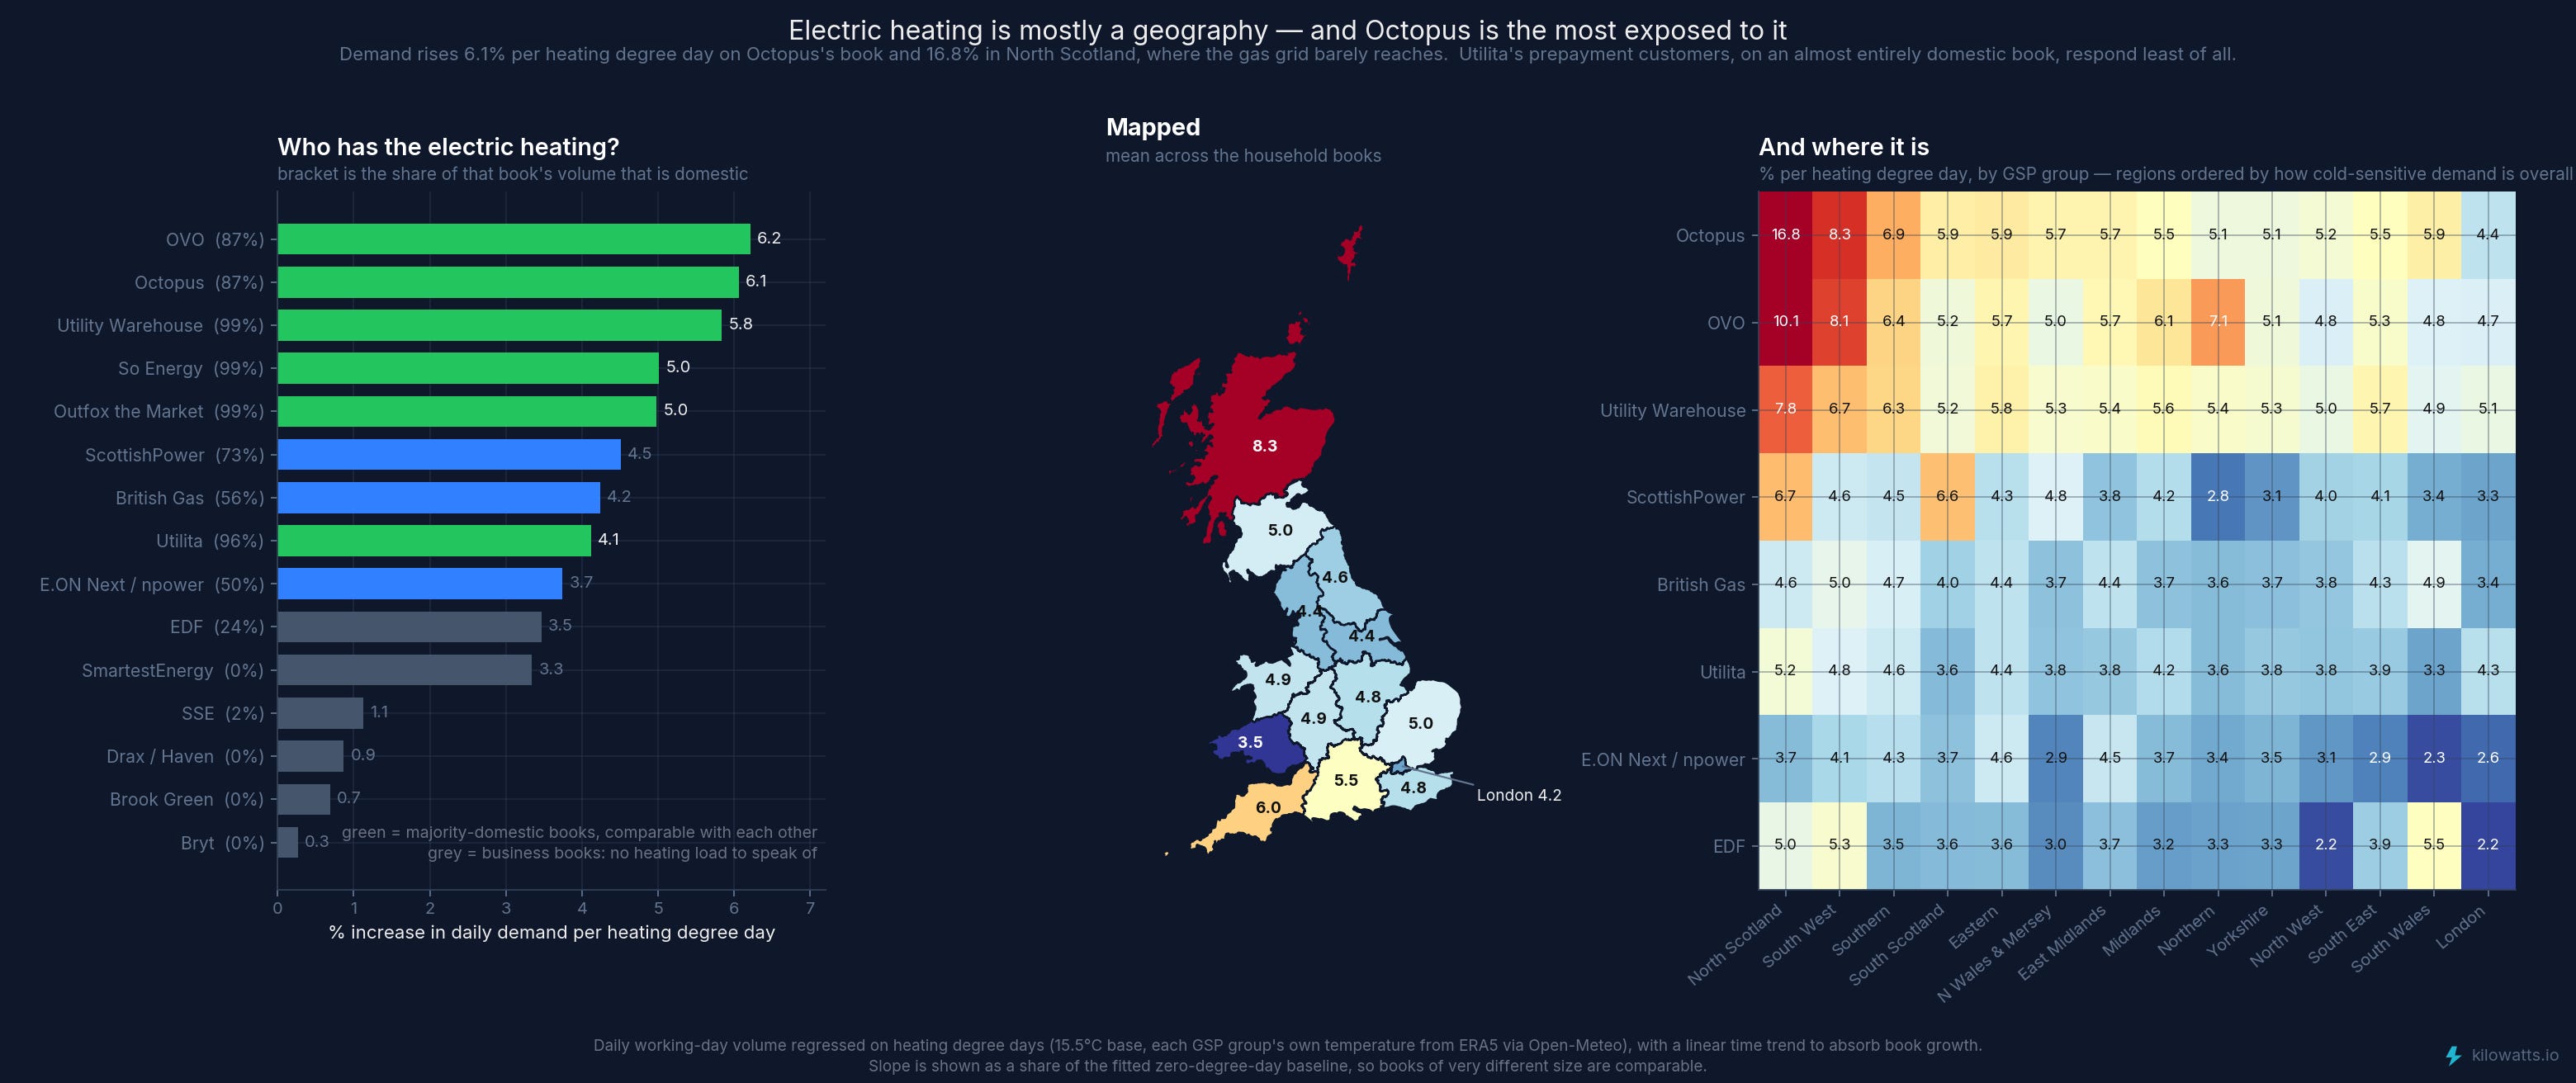
Daily volume regressed on heating degree days with a time trend, by supplier and by GSP group. Only the majority-domestic books compare fairly with each other.
That last caveat deserves its own chart, because the thing the carbon metric penalises is measurable. Regressing each book's daily demand on heating degree days gives its exposure to electric heating — and it turns out to be the sharpest regional result in the piece. Business books come in at 0.3–1.1% per degree-day; household books at 4–6%. OVO and Octopus are the most cold-sensitive majors, at 6.2% and 6.1%, against British Gas at 4.2% and E.ON at 3.7%.
And this is one place where Octopus is not pulling away. Fit the same regression separately for each of the three years and every household book except two is getting more cold-sensitive, not just Octopus: it goes from 4.9% to 6.5% per degree-day, but Utility Warehouse goes from 4.9% to 6.9% and ScottishPower from 4.2% to 5.7%. Electric heating is arriving across the residential market at roughly the same rate. Whatever is distinctive about Octopus's book, its rate of electrifying heat is not it.
The obvious objection is that this is the solar talking: panels suppress a supplier's summer volume, which would make its winter look heavier without a single extra radiator. It is not. Restrict the same test to 22:00–04:00 — hours in which no British solar panel has ever generated, in any month — and the picture holds: Utility Warehouse's cold sensitivity rises 1.6 points over three years, Octopus's 1.1, and every other household book is flat or falling. Add the estimated solar generation back to the whole day instead, and Octopus's winter volume still grows relative to its summer, with panels accounting for well under a quarter of the move. Two suppliers are heating more homes with electricity. Neither of them is doing it because of the sun.
But the real pattern is geography, not company. Averaged across the household books, North Scotland runs at 8.3% per degree-day and South Wales at 3.5% — more than twice the sensitivity, in a country you can drive across in a day. Octopus's North Scotland book alone runs at 16.8%, the highest figure in this entire analysis.
And it is emphatically not simply "colder places use more heat". Southern England is more cold-sensitive than Northern England — 5.5% against 4.6% — while being over a degree-day warmer. South Wales, the least sensitive region in Britain, sits below London. What the map is actually drawing is the gas grid: where mains gas thins out, in the Highlands and in rural Devon, Cornwall and Wessex, heat runs on the wire. Where the pipes are dense — the Valleys, London, the northern cities — it does not. This is a map of pipes, not of weather.
Act 8 — a transition for homeowners
Run back through what this article has measured. Rooftop solar. Home batteries. Electric vehicles charged overnight. Heat pumps. Every single one of them requires two things: a roof you own, and capital to put on it.
Which is why the most instructive book in the whole dataset is the one that barely moves.
Utilita supplies about 710,000 households and is Britain's largest prepayment specialist — a segment much of the market has spent years trying not to win. Its book is 96% domestic by volume, so it compares directly with Utility Warehouse and So Energy, and on every measure in this piece it sits at one end:
domestic export MPANs per 1,000 meters — Utilita: 0.23 · Octopus: 39.4
SEG solar installations, all of GB — Utilita: 89 · Octopus: 314,470
evening peak share, change over three years — Utilita: −0.6 pp · Octopus: −3.0 pp
demand response per heating degree day — Utilita: 4.1% · Octopus: 6.1%
electricity per meter per quarter — Utilita: 906 kWh · Octopus: 1,154 kWh
None of that is a failing of Utilita's. You cannot fit solar to a roof you rent. You cannot buy a battery, or an electric car, or a heat pump, on a prepayment meter and a tight month. The Smart Export Guarantee pays people who own a roof. Heat pump and EV grants reduce the cost of a purchase for people in a position to make one. Time-of-use tariffs reward households that can move consumption — which usually means households with an appliance expensive enough to be worth moving.
Read that column again and it is not a story about a company. It is the shape of a policy settlement in which the instruments of the flexibility transition are, almost without exception, available to people who own property and have money to spend on it. Utilita's book is what the transition looks like from the other side of that line.
One number deserves care rather than a punchline. Utilita's customers respond least to cold — 4.1% per heating degree day against Utility Warehouse's 5.8% on a book just as domestic. There are two readings and this data cannot separate them: those homes may simply have less electric heating, or they may be heating less when it gets cold. Self-rationing and self-disconnection among prepayment households in cold weather are well documented across the sector and are not specific to any supplier. If it is the second reading, a book that does not respond to a cold snap is not a book doing well, and that is a matter for policy rather than for the company that serves those customers.
What half-hourly settlement changes is that all of this stops being an inference. Until now the settlement record assigned these households the same national curve as everyone else — the same eight curves this article opened with. From now on it will show, in public data, month by month, exactly how far the flexibility transition has and has not reached the people it was hardest to reach.
That seems to me the most useful thing likely to come out of the reform, and it is not the eight figures a year.
Conclusions — the pack holds, one book leaves
Four things follow, in roughly descending order of confidence.
One: the market is not fragmenting. One supplier is leaving it. I went looking for eight books drifting apart and did not find them. Octopus's settled shape sat in the middle of the household pack three years ago and is now outside it on most axes measured here — the flattest evening peak, the most overnight load, ten times the solar density. Not all of them: it is second to OVO on cold sensitivity, and its rate of electrifying heat is unremarkable. But the other eight have barely moved relative to each other. Every one of them shifted less than 0.6 points of evening share in three years, against Octopus's 2.20, and none of them accelerated at migration. Several of them are closer to each other now than they were before migration began. This is not a market of near-identical retailers coming apart at the seams. It is a market of near-identical retailers, minus one — and the one is pulling away in the hours and the season where being ordinary costs the most.
Two: the averaging was an insurance policy, and it has been cancelled. Not by design, but in effect. When every household is settled against the same eight curves, each supplier is charged for the average customer rather than its own. A supplier whose customers were unusually peaky was carried by one whose customers were not, and neither could see it happening. Octopus spent years paying for an evening peak its customers did not have; its customers were subsidising peakier books. That is what profiling was — a mutual insurance scheme nobody signed up to, priced at zero, settling claims silently every half hour for twenty-five years.
Each supplier is now charged for the shape it actually has. Whoever has the flattest book stops paying for someone else's peak: worth eight figures a year to one supplier already, on one measure, one year into a transition that is 70% done. The reverse is the part that will hurt. Whoever has the peakiest book now owns that cost outright — and owning a cost is not the same as being able to do anything about it. You can no longer ride the pack. There is no pack.
That is the asymmetry, and it is where this gets interesting. Settlement now prices a supplier's shape by the half hour, while most retail tariffs still hide time from the customer completely: one unit rate, every hour of the day, all year. On Ofgem's most recent figures a majority of accounts at several large suppliers sit on price-capped default tariffs — 74% at OVO, 60% at ScottishPower, 57% at EDF — which are flat by construction. (Octopus and E.ON Next are absent from that release, which is exactly the wrong hole; see below.) Those suppliers have been handed a bill denominated in half hours and a customer relationship denominated in a single number. Nothing the customer sees tells them when to run the washing machine, so nothing the customer does will change what the supplier pays. The bill has arrived years before the lever.
Which makes this a selection event, and the trait being selected for is not the one the industry is organised around. Not scale, not brand, not the quality of your hedging desk. It is the ability to persuade several million people to move electricity into a different hour of the day — and increasingly to do it for them automatically, while they are asleep. That is a software and behavioural competence wearing an energy company's clothes. Octopus's 2.20-point move did not happen because it forecast prices better than British Gas. It happened because it built tariffs that pay people to shift, an app that makes the shift legible, and direct control of the car and the battery so that most of its customers never have to think about it at all.
The uncomfortable part for everyone else is that this cannot be bought quickly. You can acquire a book of customers, and several suppliers here have, at speed and at scale. You cannot acquire their willingness to be moved. That has to be built, tariff by tariff and app release by app release, over years — and the suppliers furthest behind are precisely the ones whose customers are most likely to be sitting on a flat default tariff they have never had a reason to leave. Three years ago that was a comfortable place to be, because the profile was doing the work. It is now a structural cost with a compounding interest rate.
Three: the cheapest way to flatten your book is to choose who is in it. Persuading millions of people to move their demand is slow, expensive and uncertain. Selecting customers who are already flat is fast, and it is free. And half-hourly settlement is what makes it possible: for the first time a supplier can put a settled, half-hourly cost against an individual customer and see what that customer is actually worth. Under profiling, a household's shape was invisible to the profit and loss account, because everyone was charged for the average one. It is not invisible any more.
Nothing crude has to happen for this to bite. No supplier needs to refuse anyone. You simply advertise the electric-vehicle tariff where electric-vehicle owners are, bid harder on the comparison sites that surface to homeowners, price the smart tariff attractively and the prepayment product adequately, and compete a little less hard to retain the customers whose evenings are expensive. Every one of those decisions is ordinary commercial behaviour, and in aggregate they sort the market by shape.
Then the same logic runs from the other direction, which is where it turns into a genuine unravelling. Flexible households will move to time-of-use tariffs, because that is where their flexibility finally gets paid for. Inflexible ones will stay on the flat default, where they are charged the same rate at six in the evening as at three in the morning. As the flexible leave, the flat pool gets peakier, and the average cost of serving whoever remains in it goes up. That is textbook adverse selection, and the exit is one-way.
Under a price cap, it does not surface as a rising price. The cap is set against a benchmark, so a supplier holding a book that is quietly getting more expensive to serve cannot simply charge for it. It surfaces as a margin, and then as a loss. Britain has already watched what happens to suppliers holding books they are not allowed to price, and it was not an orderly process.
And the residual pool is not a random draw. Every mechanism in this article — panels, a battery, a car charged at half past eleven, a heat pump — needs a roof you own and capital to put on it. The households that cannot move are renters, flat-dwellers, prepayment customers, people whose consumption is already low because it is rationed rather than optimised. Utilita's book, the one that has barely changed shape in three years, is the clearest example in the data, and it is not a failure of that supplier so much as a description of who its customers are. As measurement improves, being flexible gets cheaper to serve and being inflexible gets more expensive — and the people on the wrong side of that line are the ones already least able to cross it. Nothing in the reform causes this. It stops hiding it, and hiding it was the only thing keeping the costs pooled.
I should be clear that this is a reading of the mechanism, not an observation. Two years of settlement data show suppliers' books diverging; they do not show anyone deliberately selecting customers by shape, and I have no way to test that from P114. But the incentive is new, it is large, and it points one way.
Four: and that is still the best argument for having done it. You cannot fix a distribution you cannot see. For twenty-five years the question "which households are actually flexible, and which are not?" had no answer in public data, because the data was averaged before anyone could ask. From November 2025 it has an answer, published monthly, for free, for every supplier in Britain. Whether that gets used to design a fairer transition or simply to price the existing one more accurately is a policy choice, not a technical one — but it is now a choice somebody has to make, rather than a fact nobody could establish.
What I could not establish
Whether this is already showing up in what people pay. Ofgem publishes exactly the right series — domestic accounts by supplier, split into price-capped default tariffs and fixed — and the current snapshot has a hole in precisely the wrong place: "data as of April 2026 does not include Octopus Energy and E.On Next due to a reporting issue." The spread among those that did report is quoted in the conclusions above, and it is wide enough to be worth someone's time. But the supplier this article is largely about is missing from it, so the argument that flat default tariffs leave a supplier without a lever is a reading of the mechanism, not a measurement of it. Whether physical divergence has become commercial divergence is the obvious follow-up, and it needs one Ofgem spreadsheet that currently does not exist. There is no time series either — each chart in that release embeds a single snapshot, so the trend cannot be traced without going quarter by quarter through archived publications.
What this rests on, and what it doesn't
Five things a careful reader should know, all of which are in the piece already but are worth having in one place.
Volume, not customers. Domestic and business shares throughout are shares of energy. EDF is 24% domestic by volume and 80% by meters. Load shape is volume-weighted, so volume is the right denominator — but the phrasing means its energy, not its customer base.
Solar carbon savings are seasonal. The annual figures blend a tenfold swing: Octopus's fleet removes 11.1 gCO₂/kWh in July and 1.1 in December, so it is below the grid March–September and above it October–February. Any annual average here conceals that.
The carbon numbers are small. Octopus's solar removes 4.7% of its customers' electricity emissions; everyone else's removes under 1.5%. The grid decarbonised 23% over the same period. Supplier-level differences are real but marginal against the generation mix.
The carbon chart is electricity only. A household swapping gas for a heat pump buys more electricity, pushes its supplier up that chart, and cuts its total emissions by roughly four fifths. Act 7 is the counterweight to Act 6 and they should be read together. No adjustment for displaced gas is attempted: the data cannot separate heat pumps from resistive heating, whose credits differ threefold, and the largest electric heating loads are off the gas grid, where nothing is displaced at all.
Solar capacity is measured, its output is modelled. Install counts and sizes come from Ofgem's SEG dataset and Elexon's export MPAN counts; the half-hourly shape is national PV output scaled to each fleet. FiT-era homes, whose export was deemed rather than metered, appear in neither count — so every solar figure here is an undercount, and most so for whoever holds the legacy FiT book.
Behaviour and measurement are entangled. Splitting Octopus's 2.2-point peak move into "customers changed" and "settlement started seeing it" rests on assuming the pre-reform trend would have continued. It is an assumption.
The £11.6m is a purchasing cost, not a transfer. It values the shape at wholesale prices. Nobody writes that cheque; it is what the volume costs to buy. The per-party settlement cashflow records were parsed and do not contain it — under profiling a supplier hedges to its profiled volume, so a wrong profile generates no imbalance.
Sourcing
All public: Elexon P114 S0142 files via a portal scripting key, the Elexon MHHS dashboard, Elexon's Gross Supplier Market Share reports, the BMRS BM Unit registry, BMRS market index prices, the NESO Carbon Intensity API, Sheffield Solar PV_Live, Ofgem's Smart Export Guarantee installation dataset, and ERA5 temperatures via Open-Meteo. No commercial data.
A superb piece of analysis. Some fascinating insights